
An operating partner inherits a revenue system, not a clean slate. When a platform company or an add-on runs HubSpot, the question in front of the person accountable for revenue operations is rarely “should we use a CRM.” It is narrower and more consequential: is this instance producing reliable pipeline data, is it configured to survive an integration, and does it support the value-creation plan the deal was underwritten on. Get that wrong and the first board meeting turns into a forensic exercise about why the forecast and the actuals do not agree.
This guide is written for the buyer who already owns the budget and the accountability. It assumes you know what a CRM does. What follows is a decision framework and a set of tests for judging HubSpot for a private equity portfolio company, whether you are looking at it during diligence, in the first 100 days, or two quarters into a stalled forecast.
1. Frame the decision as an enterprise-value question, not a tooling question
A PE-backed buyer is not purchasing a CRM. It is purchasing forecast reliability, faster time-to-cash, cleaner management visibility, and a revenue engine that can absorb add-ons without breaking. HubSpot is one lever on those outcomes. Treat every configuration choice as a claim about one of them.
That reframing changes what you look at. The instance is not “good” because it has automation or “bad” because reps complain about data entry. It is good if the numbers rolling up to the board are trustworthy and the system can scale with the thesis. Bain’s annual Global Private Equity Report has documented for years how much of return generation has shifted toward operational improvement rather than multiple expansion or leverage. Revenue data quality is squarely inside that operational envelope.
So the first decision is not about HubSpot at all. It is: what does the value-creation plan need this system to do, and by when. Everything downstream is judged against that.
The three states a HubSpot instance can be in
- Load-bearing. The forecast, the pipeline, and management reporting genuinely run on it. Changing it is a project with risk.
- Decorative. Reps log activity to satisfy a manager, but the real numbers live in spreadsheets. The CRM is theater.
- Contested. Two functions, or two acquired businesses, each keep their own version of truth. The instance exists but nobody trusts it.
Most underperforming portfolio companies sit in the second or third state. Your job is to identify which, because the remediation and the cost are completely different.
2. Judge the instance during diligence, before you own the problem
Revenue tooling belongs inside technology due diligence, not as an afterthought once the deal closes. The commercial reason is simple: if the pipeline data feeding the model is unreliable, the model is unreliable, and you find that out after the wire clears.
You are not doing a full audit during diligence. You are running a small number of high-signal checks that tell you whether the revenue numbers are earned or assembled.
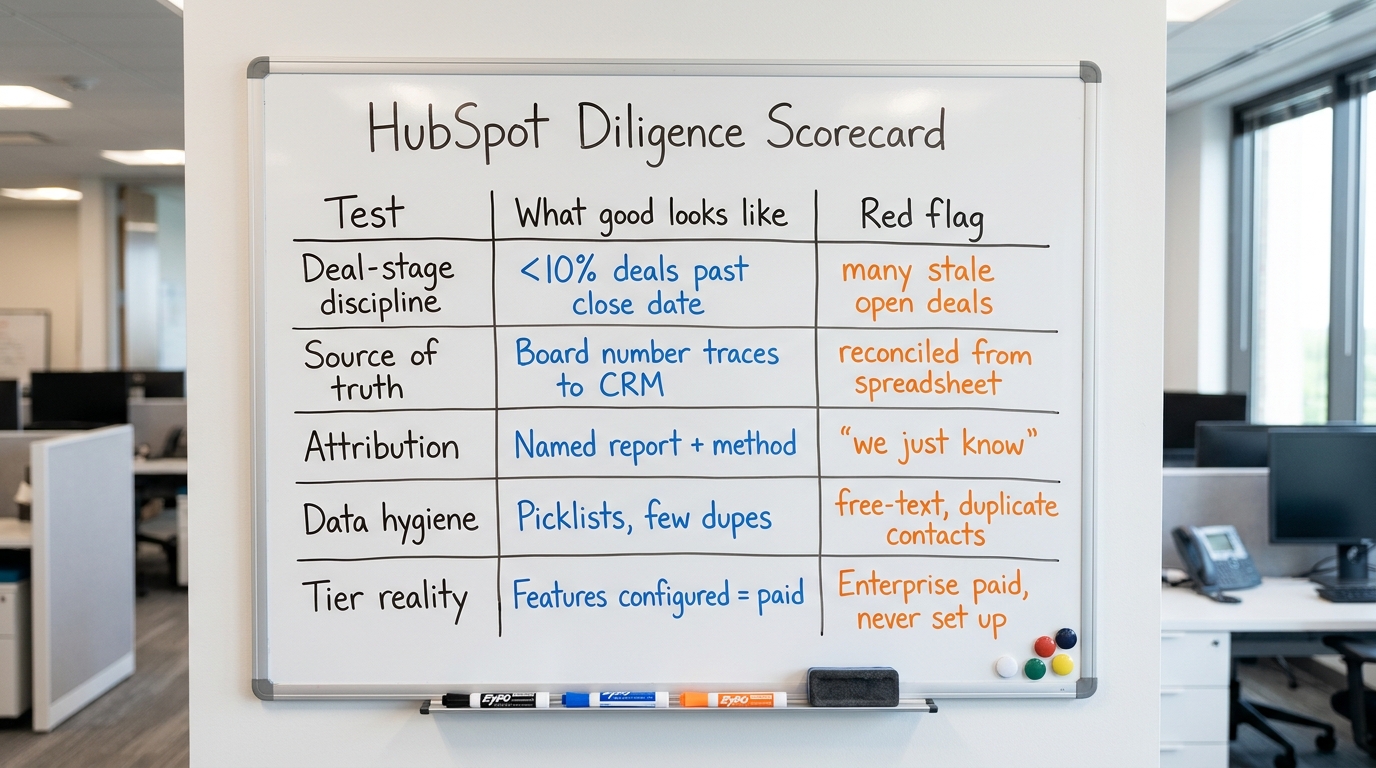
Five diligence-stage tests
- Deal-stage discipline. Pull the open pipeline. What percentage of deals have a close date in the past? A large share means the pipeline is not being maintained, and every forecast built on it is soft.
- Source of truth for revenue. Ask to see the number the CFO reports to the board and trace it back. If it comes from a spreadsheet that is manually reconciled against HubSpot, the CRM is decorative.
- Attribution honesty. Ask how they know which channels produce revenue. Vague answers are common; a defensible answer looks like a real reporting setup. This is where a working knowledge of HubSpot attribution reports for ROI measurement separates an instance that informs spend from one that just collects clicks.
- Data hygiene. Duplicate contacts, empty required fields, and free-text where there should be picklists all raise the cost of any later integration.
- Seat and tier reality. Confirm which HubSpot tier and hubs are actually licensed versus paid for. Companies frequently pay for Enterprise features they never configured.
Write findings into the risk register with a cost and an owner, not as a vague “CRM needs work.” “Pipeline hygiene remediation, roughly one quarter of RevOps effort, owner TBD at close” is something a deal team can price. “The CRM is messy” is not.
PitchBook and S&P Global Market Intelligence both maintain research on how deal teams increasingly scrutinize commercial engines rather than accepting top-line growth at face value; you can track that shift through PitchBook’s research and data and S&P Global Market Intelligence.
3. Decide whether to keep, standardize, or replace
Once you own the company, the platform decision splits three ways. Each has a different cost curve and a different risk profile.
Keep and remediate
Appropriate when the instance is load-bearing or fixable, and HubSpot is a reasonable fit for the company’s motion. This is the cheapest path in cash terms but demands discipline, because a neglected instance does not improve on its own. The work is pipeline hygiene, reporting you can trust, and closing the gap between logged activity and reported revenue.
Standardize across the portfolio
Appropriate when a platform is buying similar add-ons and wants one revenue system so it can compare businesses on the same definitions. The payoff is management visibility: a common instance means “qualified pipeline” means the same thing in every unit. The cost is migration and change management, and the temptation to over-engineer a template that fits nobody. McKinsey’s private capital research and BCG’s principal investors and private equity practice both publish repeatedly on the value of repeatable operating playbooks across a portfolio, and a shared CRM standard is one of the more concrete versions of that idea.
Replace
Appropriate only when the platform genuinely cannot support the motion, not because a new sponsor prefers a different vendor. Replacement is the most expensive and riskiest option: it consumes RevOps capacity in the exact window when the company should be executing the plan. Reserve it for a real structural mismatch, and price it honestly in the risk register.
The default for most lower-middle-market and mid-market companies is keep and remediate, followed by standardize as add-ons arrive. Replacement should be the exception that a specific fact forces on you.
4. Fix the data before you touch the automation
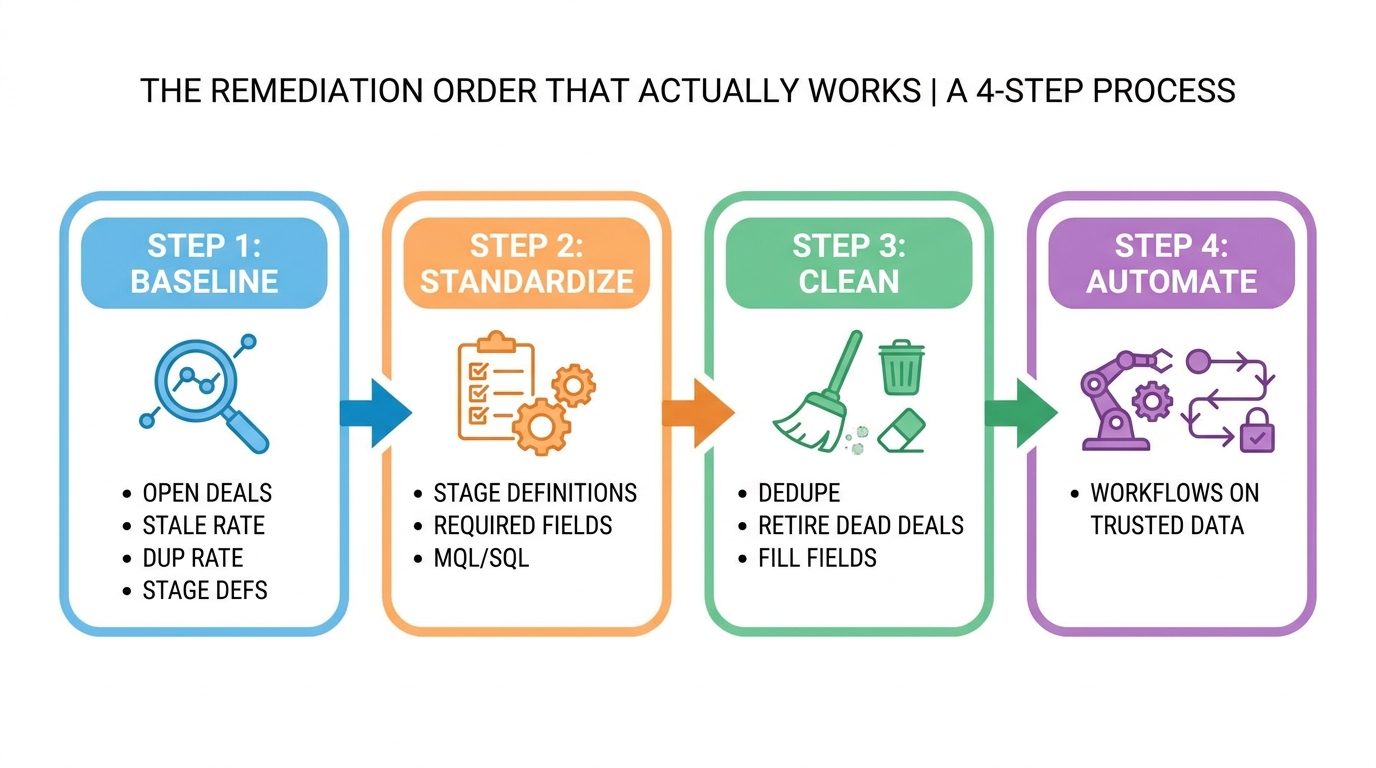
The most common mistake in the first 100 days is building shiny workflows on top of dirty data. Automation applied to bad data produces bad outcomes faster. Sequence matters.
Set the baseline first
Before changing anything, capture the current state: number of open deals, share with valid close dates, duplicate rate, and the current definition of each pipeline stage. That baseline is what you measure remediation against, and it is what protects you when someone later claims the numbers “always looked like this.”
Standardize the definitions
A pipeline stage that means “we had a call” in one team and “they signed a term sheet” in another cannot roll up into a portfolio number. Nail down stage definitions, required fields, and what a qualified lead actually is. This is unglamorous and it is the single highest-leverage work in the entire exercise.
Then clean, then automate
Deduplicate, fill required fields, retire dead deals, and only then build automation on top of a foundation you trust. The order is baseline, definitions, cleanup, automation. Reversing it is how portfolio companies end up with elaborate workflows nobody trusts.
Understanding the buyer on the other end of the pipeline helps here too. If lead scoring and qualification are going to mean anything, they have to reflect how the company’s actual customers decide, which is a lesson in niche buyer psychology more than a lesson in software.
5. Build reporting the board will actually rely on
The purpose of a portfolio CRM is not activity tracking. It is a forecast the board can hold management to and a view of where revenue actually comes from. Two reporting jobs matter above everything else.
A forecast that ties to actuals
The forecast in HubSpot and the number in the board deck should be the same number, derived the same way. When they diverge, trust in the entire system collapses, and the operating partner ends up rebuilding it by hand every quarter. Judge the instance by whether actual-versus-plan can be produced from the CRM without manual reassembly.
Attribution that informs spend
Marketing spend inside a portfolio company should be defensible at the channel level. If nobody can say which channels produce closed revenue, the marketing budget is a guess. Well-built attribution reporting closes that gap and turns spend arguments into evidence-based decisions. The attribution reporting guide referenced earlier covers the mechanics; the operating point is that a CFO who cannot see channel-level return will, correctly, treat the marketing line as discretionary.
Harvard Business Review’s coverage of mergers and acquisitions and the Harvard Law School Forum on Corporate Governance both return often to the theme that management reporting reliability is a governance issue, not just an operational nicety. In a PE context, the board’s confidence in the forecast is part of the asset.
6. Protect the pipeline from cosmetic distortions
A pressured revenue team will find ways to make the numbers look better without making them better. This is not fraud; it is the predictable response to being measured. The operating partner has to build reporting that resists it.
Two patterns show up repeatedly. First, pipeline inflation, where deals with no real chance sit in the funnel to hit an activity target. Second, review and reference gaming, where customer proof is manufactured rather than earned. The latter has real downside beyond vanity metrics; platforms penalize it, and the exposure is worth understanding through the mechanics laid out in why incentivized reviews trigger platform penalties. A portfolio company caught gaming reviews carries a reputational and compliance risk that surfaces at exactly the wrong moment.
The defense is definitional discipline and reporting that a third party could reproduce. If a number cannot survive an outsider recreating it from the CRM, it is not a number you want in a board deck.
7. Get the first 100 days sequence right
The first 100 days set the tone for whether the revenue system becomes an asset or a permanent argument. The temptation is to do everything at once. Resist it. Sequence for early, verifiable wins that build trust in the data.
Days 1 to 30
Establish the baseline, secure access and admin control, and identify the actual source of truth for the board number. Do not change anything yet. You are confirming what you bought.
Days 31 to 60
Standardize stage definitions and required fields. Begin cleanup. Stand up the first version of a forecast that ties to actuals, even if it is imperfect, so the board has one number by the first board meeting.
Days 61 to 100
Layer in automation and attribution reporting on the now-trusted foundation. Document the operating cadence so it survives without heroics. If the plan calls for standardizing across add-ons, this is where the template gets designed, once, from a working reference instance.
Preqin’s alternative assets data and reporting in Private Equity International, Buyouts, and PE Hub all reflect the same pressure on hold periods and value creation timelines: the window to establish operating discipline is short, and revenue reporting is one of the fastest levers to move within it.
8. Judge the people and process, not just the platform
A well-configured HubSpot instance with no owner degrades within a quarter. The platform decision is inseparable from a staffing and accountability decision.
Who owns RevOps
Someone has to own the definitions, the data quality, and the reporting. In a lower-middle-market company that role may be a fraction of a person or an outside partner, but the decision right has to sit somewhere specific. Ambiguity here is why instances drift back into the decorative state.
Adoption is a leading indicator
If reps route around the system, the data will always be wrong no matter how clean the configuration. Adoption is not a soft metric; it is the leading indicator of whether the forecast will hold. Companies that treat their revenue tooling as part of a coherent brand and customer experience, rather than an internal chore, tend to see better adoption, which is one reason the discipline of building trust through the customer experience and consistent content for service brands matters even at the operations layer.
9. Know when standardization actually pays and when it does not
Standardizing HubSpot across a portfolio is attractive on paper and expensive in practice. It pays when the businesses share a motion and the platform wants comparable numbers. It fails when a template is forced onto businesses that sell differently, because reps abandon a system that does not fit their work.
The commercial test is whether comparability creates decisions. If a shared instance lets the platform reallocate spend, benchmark units, and diligence the next add-on faster, standardization earns its cost. If it just produces uniform dashboards nobody acts on, it is overhead. Add-ons that bring their own customers and channels may benefit more from disciplined audience alignment across the combined businesses than from a forced platform merge on day one.
Where the businesses are genuinely different, a lighter standard, shared stage definitions and a shared reporting layer, can deliver most of the visibility benefit without a full migration. That is often the better answer for a diverse portfolio.
10. The checklist an operating partner can act on
Use this as the working checklist across diligence and the first 100 days. It is deliberately about outcomes and evidence, not features.
- State. Is the instance load-bearing, decorative, or contested? Name it before deciding anything.
- Source of truth. Does the board’s revenue number trace to the CRM, or to a spreadsheet?
- Baseline. Open deals, stale-date rate, duplicate rate, and stage definitions captured before any change.
- Definitions. Stage meanings and qualification criteria standardized and written down.
- Sequence. Baseline, then definitions, then cleanup, then automation. Never automation first.
- Forecast. Actual-versus-plan producible from the CRM without manual reassembly.
- Attribution. Channel-level return visible enough to defend the marketing line to the CFO.
- Integrity. Reporting a third party could reproduce; no pipeline inflation, no gamed reviews.
- Owner. A specific person or partner holds the RevOps decision right.
- Adoption. Reps use the system as their real workspace, not a reporting chore.
- Standardization. A shared instance only where comparability drives actual decisions.
If you cannot answer these confidently, the instance is not yet an asset the board can rely on, and the value-creation plan is exposed at the revenue line. The good news is that the remediation is well understood and comparatively cheap against the enterprise value it protects.
This work sits inside the broader operating agenda that a private equity operating partner runs across a portfolio, from diligence through exit preparation. Getting the revenue system right early is one of the more reliable ways to make the forecast trustworthy, the visibility real, and the next add-on faster to absorb.
Route the decision to a team that has done it
If you are judging a portfolio company’s HubSpot instance in diligence or fixing one in the first 100 days, and you want a scoped RevOps engagement that turns the checklist above into a working system, review the DevriX private equity operating offer and bring the specific instance and value-creation plan you are working against.