
By the time an operating partner is staring at a revenue forecast that assumes 30 percent net new growth, the question is no longer whether the target has a good product. The question is whether the go-to-market engine can actually produce the number the model already promised the LPs. That is what RevOps due diligence in private equity is for. It is not a technology audit and it is not a sales headcount review. It is a judgment about whether the commercial machine can hit plan, at what cost, and how much of the gap is fixable inside the hold period.
The reader here is the person who inherits the answer: the operating partner running the value-creation plan, or the portfolio executive who has to defend the pipeline at the first board meeting. Get RevOps diligence wrong and the forecast becomes a covenant problem three quarters after close. Get it right and the first 100 days start with a ranked list of fixable constraints instead of a mystery. This guide covers what to decide, in what order, and how to judge the evidence without taking the seller’s dashboard at face value.
1. Decide what the forecast actually depends on
Most revenue models sold in a data room rest on three or four load-bearing assumptions that nobody has stress-tested. Before touching a CRM, write those assumptions down. A typical growth case assumes some combination of higher lead volume, better conversion from lead to close, larger deal sizes, faster sales cycles, and lower churn. Each is a separate operating claim, and each has a different owner and a different failure mode.
The commercial consequence of skipping this step is that diligence turns into a data-cleaning exercise instead of a decision. The point of RevOps due diligence in private equity is to tie every dollar in the model to a mechanism you can inspect. If the plan needs 20 percent more pipeline, the diligence question is not “is marketing good,” it is “which channel produces that pipeline today, at what CAC, and what breaks when you double the spend.”
Bain’s annual work on value creation, published through its Global Private Equity Report, has repeatedly made the point that returns increasingly depend on operational improvement rather than multiple expansion or leverage. That shifts the burden onto commercial execution, which is exactly what RevOps diligence measures.
Separate the growth case from the base case
Split the model into two columns. The base case is the revenue the business produces if nothing changes: existing customers, existing motion, existing team. The growth case is everything the thesis adds on top. Diligence should be brutal about the base case (is it real, is it durable) and skeptical about the growth case (is the mechanism proven anywhere, or is it a slide). Founders and sellers routinely blend the two so that fragile upside looks like a running business.
2. Build the revenue baseline from source data, not slides
The single most valuable output of RevOps diligence is a defensible baseline: what the business actually does today, measured from the systems of record rather than the seller’s summary deck. This is the number your value-creation plan is measured against, so its integrity matters more than any projection.
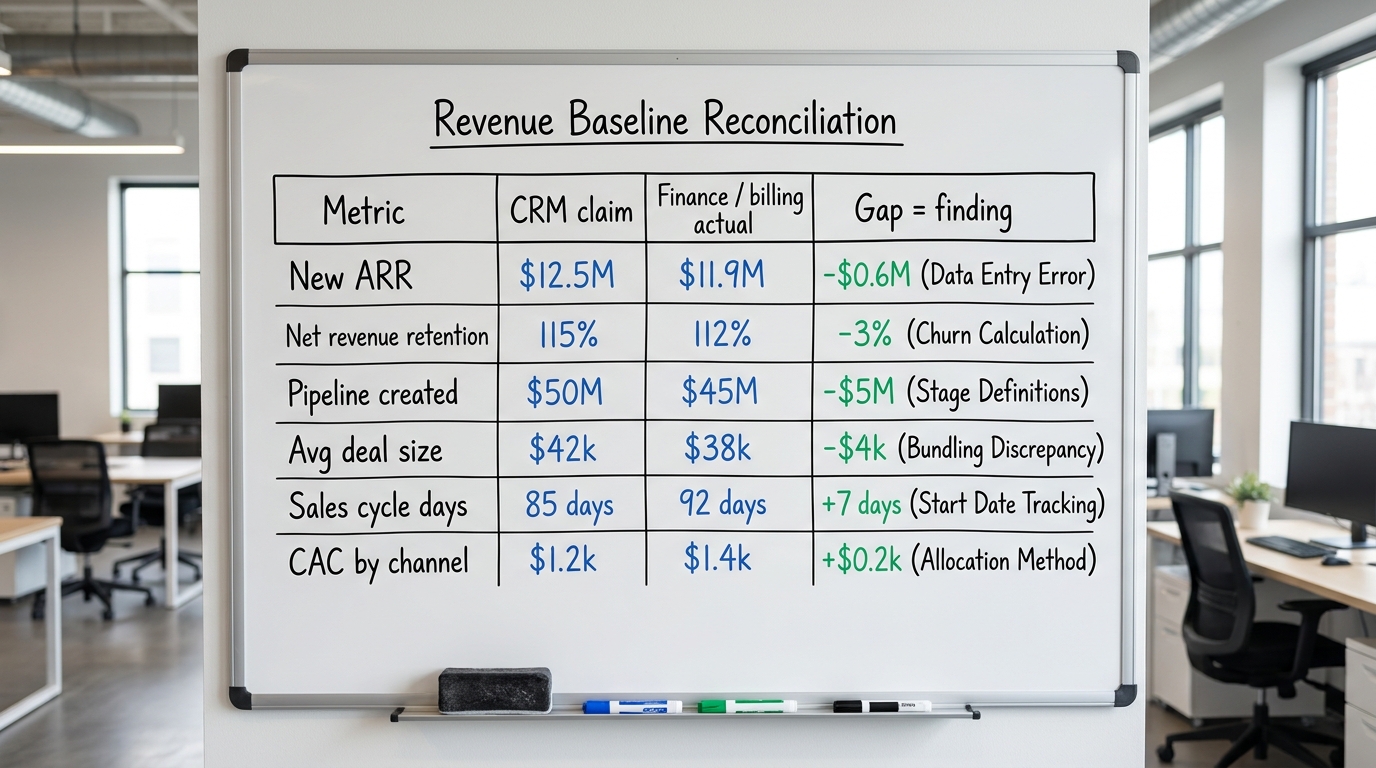
Pull the raw data. Closed-won by month for at least eight quarters. New logo versus expansion versus renewal. Gross and net revenue retention by cohort. Pipeline created by source, stage conversion, and average sales cycle. Then reconcile it against the billing system and the audited financials. When the CRM says one thing and the finance system says another, the gap is the finding. The American Institute of CPAs, through AICPA & CIMA, sets the quality-of-earnings standards that finance diligence leans on. RevOps diligence should reconcile to that QoE, not float beside it.
Watch for the classic distortions. Revenue recognized on multi-year contracts booked as if annual. Pipeline inflated by stale opportunities that never closed and never got marked lost. Retention numbers that quietly exclude the accounts that left. Attribution claims that credit paid media for demand that a partner relationship actually created. If the seller cannot reproduce a headline metric from raw exports in front of you, treat it as marketing, not evidence.
3. Judge the pipeline before you trust the growth case
Pipeline is where optimism hides. The growth case almost always assumes the top of funnel scales, so the diligence job is to find out whether current pipeline is healthy and whether it can be enlarged without collapsing quality.
Coverage and velocity
Look at pipeline coverage against quota by segment, not in aggregate. A blended 3x coverage can hide a healthy enterprise motion sitting on top of a broken SMB one. Then look at velocity: how long deals sit in each stage, and whether conversion rates have been drifting. Deteriorating stage conversion is an early warning the model rarely prices in, because the seller shows you the trailing win rate, not the leading one.
Source concentration and durability
Ask where pipeline comes from and how durable that source is. A business that produces most of its qualified pipeline from one channel, one partner, or one founder’s network has concentration risk that the growth case treats as if it were infinitely scalable. This is where marketing attribution earns its keep. If the target runs HubSpot, the way it structures HubSpot attribution reports for ROI measurement tells you fast whether they actually know which activity produces revenue or whether they are guessing. Teams that cannot attribute pipeline cannot scale it predictably, and a growth case built on unattributable demand is a coin flip.
Be equally skeptical of reputation-driven pipeline. If a chunk of demand rides on reviews and social proof, verify how those reviews were obtained. Programs that lean on incentivized reviews that trigger platform penalties are a latent liability that can vaporize a lead source overnight, and they do not show up in any pipeline report until the platform acts.
4. Test the go-to-market motion for repeatability
A number can be real and still be unrepeatable. The diligence question is whether the revenue was manufactured by a system or by a few heroic individuals. Systems survive an ownership change; heroes often leave within a year of it.
Score the motion on three axes. First, is the ideal customer profile defined and enforced, or does the team sell to anyone with a budget? Loose ICP inflates near-term revenue and destroys retention later. Sellers with a disciplined view of buyer psychology, the kind covered in this guide to niche buyer psychology, tend to produce cleaner cohorts and better net retention. Second, is the playbook documented and coachable, or does it live in the head of the VP of Sales? Third, does the marketing generate demand or merely capture it? A brand that has built genuine trust through its content, along the lines of this work on building trust through emotional marketing, has a demand asset that survives a leadership transition. A brand that only buys clicks has a spend line that stops working the day the budget tightens.
Ramp and rep economics
Pull the ramp curve for sales reps: how long until a new hire hits quota, and what percentage ever do. The growth case that assumes doubling the sales team assumes those hires ramp at historical rates. If only half the current reps carry the number, hiring more of the same is not a growth plan, it is a payroll increase. This is one of the most common ways a plausible model quietly falls apart in year one.
5. Assess the RevOps stack as an EBITDA and risk question
The systems matter, but not for the reasons a technologist cares about. For the operating partner, the stack is a question of forecast reliability, integration risk, and how much manual labor is currently propping up the reported numbers. This is where RevOps diligence connects to the broader technology due diligence workstream, and the two should share findings rather than run blind to each other.
The three practical questions:
- Is the data one version of the truth or several? When CRM, marketing automation, billing, and the finance system disagree, someone reconciles them by hand every month. That labor is a hidden cost and a source of forecast error. It also means every board number carries an asterisk.
- How much of the reported performance depends on a spreadsheet? Manual pipeline scrubs and hand-built commission calculations are fragile, error-prone, and do not scale. They are also a Day 1 operating risk if the person who runs them leaves.
- What breaks under an add-on? If the thesis includes acquisitions, the ability to onboard an acquired company’s revenue data into a single system becomes an integration dependency. A stack that cannot absorb an add-on turns a two-quarter integration into a two-year one.
McKinsey’s private capital research, available through the firm’s insights, has consistently linked value creation to operational discipline and data-driven management. A RevOps stack that cannot produce a reliable weekly number is not a technology inconvenience, it is a management-visibility gap that shows up at every board meeting for the length of the hold.
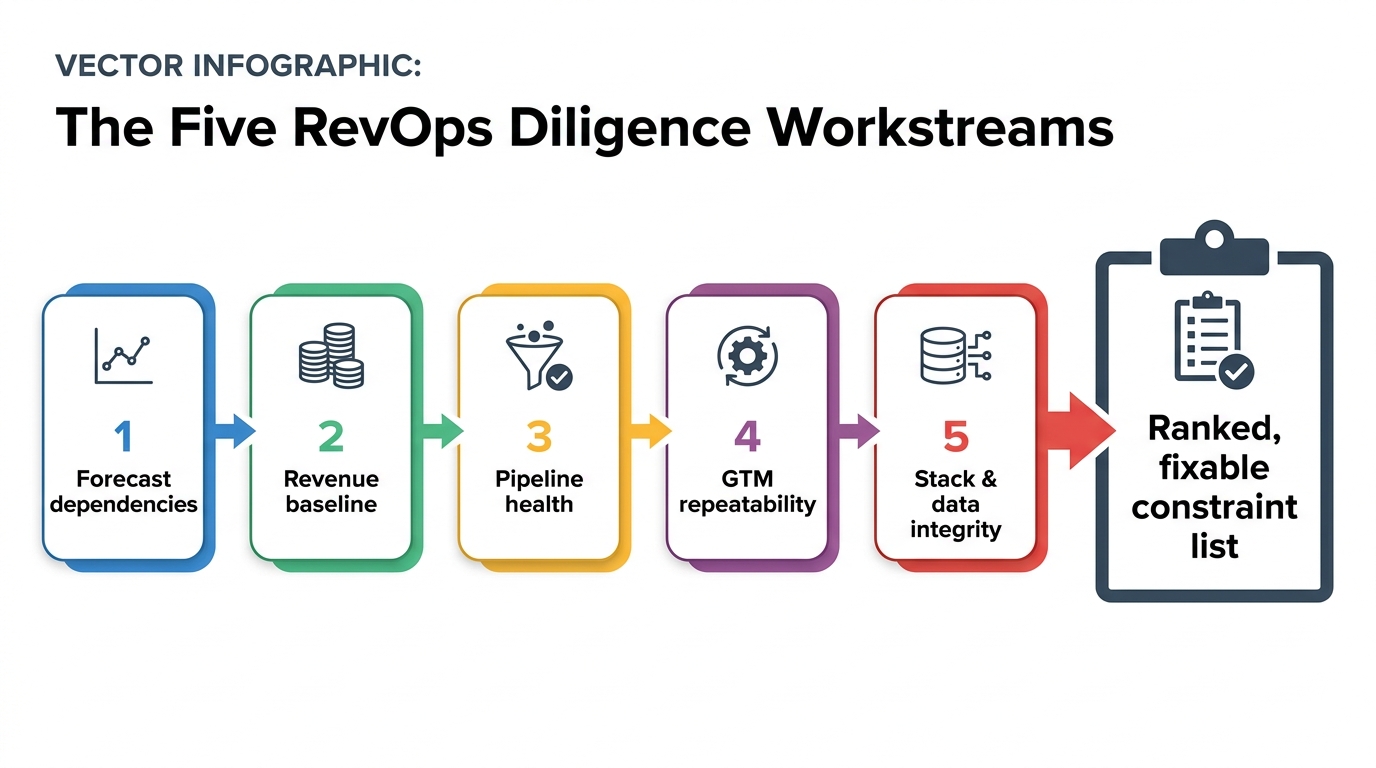
6. Quantify the gap between actual and plan
Everything to this point produces raw findings. This step turns them into a decision. Take the growth case from Section 1 and, for each assumption, mark it as supported, partly supported, or unsupported by the evidence. Then attach a rough cost and timeline to closing each gap.
Classify the value at stake honestly. Some improvement is realized the moment ownership changes, because it fixes a measurement error rather than the business. Some is run-rate, achievable once a fix is in place. Some is forecast, dependent on execution that has not started. And some is simply risk avoided, where the diligence keeps the deal team from funding a number that was never real. Blending these together is how models overpromise. A findings memo that says “we can add 8 points of net revenue retention” means nothing until it states whether that is realized, run-rate, or a forecast riding on a playbook the team has never run.
PitchBook’s data and research and S&P Global Market Intelligence both track how entry multiples and hold-period returns move, and the pattern is consistent: when entry prices are high, the return has to come from operations, which means the RevOps gap analysis is not a nice-to-have, it is the core of the underwriting.
Write the finding as a decision, not an observation
“CRM data is messy” is an observation. “Reported net new ARR is overstated by roughly 12 percent because expansion is booked as new logo, which means the true base is lower and the growth-case starting point should be revised down” is a decision input. Every diligence finding should end with the decision it changes: price, plan, or pass.
7. Separate quick wins from structural fixes for the first 100 days
The output the operating partner actually needs is a sequenced plan, not a report. Sort every finding into two buckets. Quick wins are changes that improve visibility or conversion inside a quarter without re-architecting anything: cleaning the pipeline definitions, fixing attribution so spend goes to what works, tightening ICP enforcement, standing up a weekly forecast that reconciles to finance. Structural fixes are the multi-quarter jobs: replatforming a broken stack, rebuilding the demand engine, or re-segmenting the entire go-to-market.
This sequencing is what feeds the first 100 days plan. The value of front-loading the quick wins is that they buy credibility and cash flow to fund the structural work, and they give the first board meeting a set of measurable improvements rather than a list of problems.
Cheap wins that show up fast
For portfolio companies that sell locally or through partners, some of the highest-return early moves are unglamorous. Tightening how the brand captures demand with emotion-driven content for local service brands, or fixing a partner motion with a disciplined approach to co-marketing and audience alignment, can lift qualified pipeline without new headcount. A referral engine that is structured around margin, using something like this framework for picking referral rewards that fit margin, is another lever that improves CAC quickly and does not require a systems overhaul.
8. How to judge the diligence itself
The operating partner is often not the person running the RevOps diligence, but they are accountable for the decision it informs. So the last skill is judging the work product. Weak RevOps diligence has tells.
- It reports activity instead of consequence. If the memo lists tools, campaigns, and headcount without connecting any of it to revenue, retention, or CAC, it is a vendor inventory, not diligence.
- It cannot reconcile to finance. Any revenue claim that does not tie to the quality-of-earnings work is a parallel story, and parallel stories are how surprises happen after close.
- It grades everything the same. Good diligence ranks findings by dollar impact and confidence. A flat list of 40 issues is a symptom of not having made the hard calls.
- It confuses forecast with realized value. If the upside reads as if it is already in the run rate, discount it.
Governance-focused readers will find the Harvard Law School Forum on Corporate Governance and the M&A coverage at Harvard Business Review useful for how boards frame post-close accountability, which is ultimately what the diligence feeds. For those who want to track how commercial diligence practice is evolving across the industry, Preqin, Private Equity International, and BCG’s principal investors work are reliable places to watch the shift toward operational underwriting. And when a filing question comes up, the U.S. Securities and Exchange Commission remains the primary source rather than a secondary summary.
9. A practical RevOps due diligence checklist
Use this as a working list against any target. Each item should end in a finding tied to a decision.
- Written list of every load-bearing assumption in the growth case, each with an owner and a mechanism.
- Revenue baseline built from raw system exports and reconciled to the quality-of-earnings work.
- New logo, expansion, and renewal revenue separated cleanly, with net and gross retention by cohort.
- Pipeline coverage, stage conversion, and velocity by segment, not blended.
- Pipeline source concentration identified, with durability judged for the top two or three sources.
- Attribution integrity checked: can the team prove which activity produces revenue?
- Review and social-proof programs audited for platform-penalty exposure.
- ICP definition, playbook documentation, and rep ramp economics assessed for repeatability.
- RevOps stack judged on single-source-of-truth, manual dependencies, and add-on readiness.
- Every finding classified as realized, run-rate, forecast, enabled, or risk avoided.
- Findings ranked by dollar impact and confidence, then sorted into quick wins and structural fixes.
- A sequenced first-100-days plan that leads with the credibility-building quick wins.
One more discipline worth adopting: when the diligence produces visuals for the investment committee, keep them legible and honest. The same rules that make a public social media infographic land, and the care that goes into logo integration in infographics, apply to an IC deck. A chart that hides the gap between actual and plan is not persuasion, it is a future problem. And once the deal closes, standing up something like a real-time feedback loop to boost reviews is one of the cleaner early proof points that the commercial engine is being managed rather than just reported.
10. What the diligence should leave you holding
Done properly, RevOps due diligence in private equity hands the operating partner three things: a revenue baseline they can defend at any board meeting, a ranked list of fixable constraints with dollars and timelines attached, and a clear separation between the value that is already real and the value that still has to be earned. That is the difference between funding a number and funding a plan.
The failure mode is treating this as a checkbox that happens once, in the data room, and never gets revisited. The baseline you build in diligence is the same baseline you manage against in the hold. The teams that carry it forward, rather than filing the memo and starting fresh at close, are the ones whose first 100 days start from evidence instead of from scratch.
If a target’s RevOps diligence needs to be run, or a portfolio company’s baseline and demand engine need to be rebuilt inside the hold period, work with the DevriX private equity team on RevOps diligence and value-creation execution.