
When a portfolio company closes an add-on, the deal model assumes two things happen quickly: the combined entity starts reporting on one set of numbers, and the promised cost and revenue synergies show up in cash. Both depend on systems integration, and both stall when the wrong person is running it. The operating partner who signed off on the thesis now owns a live problem. Order-to-cash runs on two ERPs. The CRMs do not talk. Finance is closing the month in spreadsheets because the general ledgers were never mapped. Every week that drags on pushes synergy realization to the right and erodes the return the model priced.
This is the decision a systems integration post merger consultant is hired to solve, and it is a decision the buyer should make deliberately, not reflexively. The wrong hire burns the first 100 days on discovery and hands back a slide deck. The right one arrives with a sequence, an owner for each workstream, and a way to show the CFO that actual is tracking to plan. This guide is written for the person accountable for that outcome: the operating partner, the portfolio CFO, or the RevOps lead carrying the integration on top of the day job.
1. Name the problem before you name the vendor
The commercial consequence of a stalled integration is specific, and it is worth stating in the terms your investment committee uses. Synergies that were underwritten as realized in year one slip into forecast. Management loses visibility because there is no single source of truth for revenue, margin, or pipeline. Working capital gets trapped in duplicate processes. And integration risk that was flagged in diligence, but never closed, turns into an operating incident.
Bain’s annual private equity report has tracked for years how much of a deal’s value creation now depends on operational execution rather than multiple expansion, which is the context in which post-merger systems work matters. You can review the current edition of the Bain & Company Global Private Equity Report for the macro picture. The practical point for the operator is narrower: integration is where a good thesis quietly leaks value, and the systems layer is where it leaks fastest.
So before evaluating anyone, write down the three or four outcomes that must be true at a defined date. For example: one general ledger and one monthly close by the end of quarter two; a single CRM with clean pipeline by Day 90; order-to-cash running on one system before peak season. If the outcomes are vague, the consultant will scope to activity, and activity is what you will pay for.
2. Distinguish this role from the ones next to it
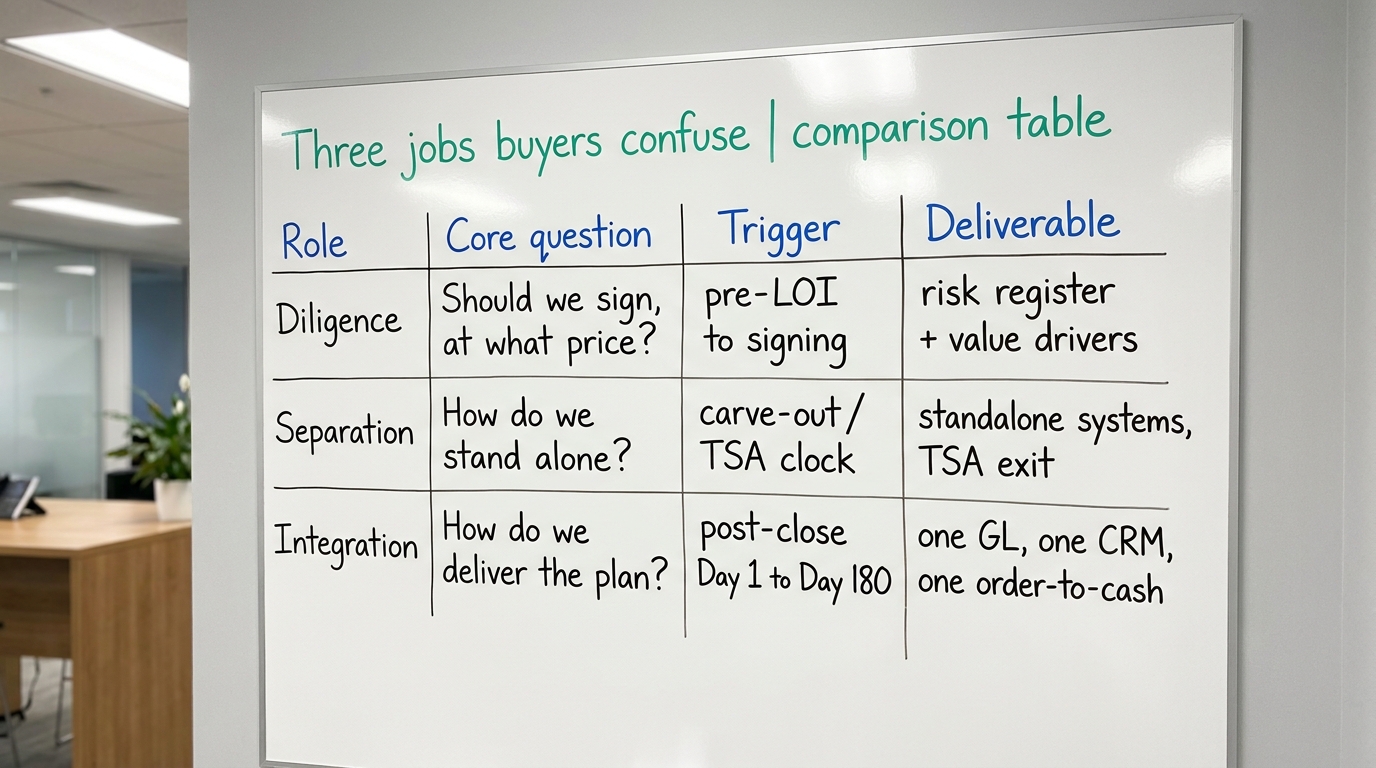
Buyers conflate three jobs that require different skills, and the confusion produces mis-hires. Systems integration post merger is not the same as carve-out IT separation, and it is not the same as pre-close diligence.
Integration versus separation
A carve-out consultant untangles a business from a parent’s shared systems, stands up standalone capability, and manages the exit from a transition services agreement. That is a subtractive, deadline-driven job governed by the TSA clock. If your situation is a divestiture rather than a bolt-on, you want that skill set, and the criteria differ enough that it deserves its own evaluation. The companion piece on how to hire and judge a carve-out IT separation consultant covers that case directly.
Integration versus diligence
Diligence answers “should we sign, and at what price,” and it flags the integration risks. The integration consultant answers “how do we deliver the plan the diligence assumed.” The two are complementary, and the best integration work starts from the diligence findings rather than re-running them. If the deal is still pre-signing, the earlier discipline is captured in digital due diligence for acquisition and in DevriX’s approach to technology due diligence. Post-close integration inherits that work; it does not repeat it.
The clean version of the distinction: separation removes, diligence decides, integration delivers. A consultant strong in one is not automatically credible in the others.
3. Decide the integration model before you scope the work
The single most consequential decision the buyer makes is not who to hire but which integration model the deal requires. That choice determines scope, timeline, and the profile of consultant you need.
- Absorb. The acquired business moves onto the platform company’s systems. Fastest to a single source of truth, hardest on the acquired team’s adoption, and the default for most bolt-ons in a buy-and-build thesis.
- Best-of-breed. The combined entity keeps the stronger system in each function and retires the rest. More analysis, more migration, and only worth it when both sides bring genuinely differentiated capability.
- Coexist. Both run in parallel behind an integration layer, with consolidation deferred. Sometimes the right answer for a platform still doing multiple add-ons, and often an excuse to avoid a hard decision.
A capable consultant will pressure-test which model the thesis actually implies rather than defaulting to whichever they sell most often. McKinsey’s private capital research and BCG’s principal investors practice both publish on why integration approach, not integration effort, drives outcomes; the material at McKinsey and BCG is useful for framing the trade-off with your deal team. The buyer’s job is to force the model choice into the open in the first two weeks, because everything downstream is priced off it.
4. Sequence the workstreams the way finance and revenue actually feel them
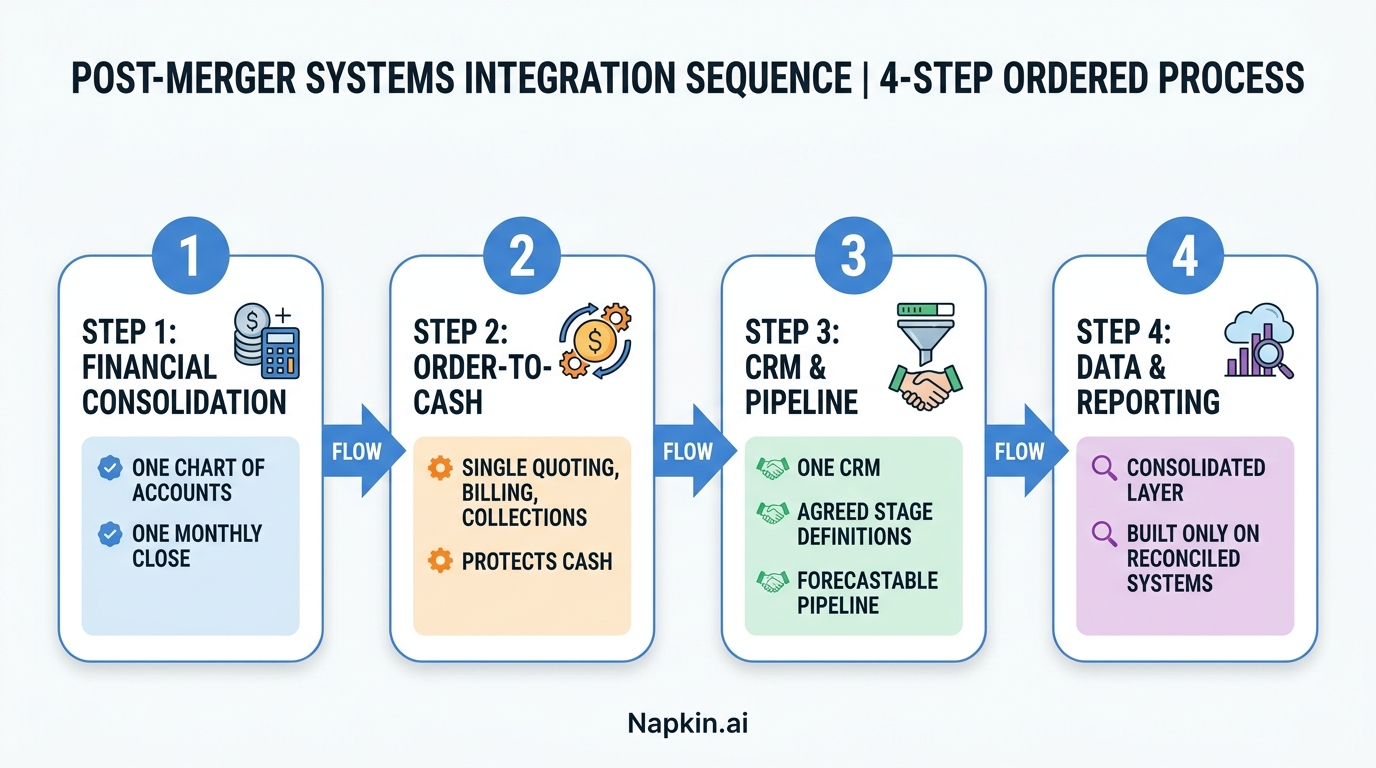
Integrations fail when everything is treated as equally urgent. The buyer should insist on a sequence tied to what the business and the board feel first. A workable order for most add-ons looks like this.
Financial consolidation first
The board needs combined numbers. Map the chart of accounts, agree the consolidation method, and get to one monthly close on a predictable calendar. Nothing else buys as much management credibility as a clean, on-time combined close. Guidance from AICPA & CIMA is a reasonable reference point for the accounting rigor this workstream demands.
Order-to-cash and revenue systems next
Duplicate quoting, billing, and collections trap cash and confuse customers. Consolidating order-to-cash protects revenue and working capital at the same time. This is where RevOps ownership matters, and where the buyer should expect a named owner rather than a committee. The related discipline of RevOps due diligence in private equity sets out what “clean pipeline and clean billing” should actually mean.
CRM and pipeline visibility
Sales leadership cannot forecast across two CRMs. A single pipeline with agreed stage definitions is what makes the revenue synergy in the model measurable rather than aspirational.
Data and reporting layer
Only after the transactional systems are settled does a consolidated reporting layer make sense. Building dashboards on top of un-reconciled systems produces confident, wrong numbers. When this workstream is large, treat it as its own program, informed by data platform implementation in a portfolio company.
5. What a systems integration post merger consultant should bring to the table
By the time you are interviewing, you are buying against outcomes, not credentials. A credible systems integration post merger consultant shows up with a small number of things that separate operators from slide-makers.
A baseline they build fast
Within the first two to three weeks they should have documented the current state of both estates: what systems exist, who owns them, where the data lives, and where the process breaks. If discovery runs past a month, the engagement is drifting.
A dependency map, not just a task list
Integration work is a chain of dependencies. The consultant should be able to show what blocks what, which items sit on the critical path, and where a slip in one workstream pushes the combined close or the synergy date. A task list without a dependency map is a false sense of control.
A synergy tracker tied to the deal model
The best integration leads translate technical milestones into the finance language of the deal. When the order-to-cash consolidation lands, they can tell the CFO which line of the synergy plan moves from forecast to realized. If a consultant cannot connect their Gantt chart to enterprise value, they are running an IT project, not an integration.
A risk register they actually maintain
Integration risk that was noted at signing needs an owner and a closure date. A living risk register, reviewed at every steering meeting, is the difference between managing risk and discovering it during the first board meeting after close.
6. Structure the engagement so incentives point at the outcome
How the work is bought shapes what you get. A few structural choices matter more than the day rate.
Fixed outcomes over open-ended time and materials
Where the outcome is definable, and post-merger integration usually is, scope to milestones with acceptance criteria. “One monthly close by end of Q2, accepted by the CFO” is a milestone. “Advisory support on finance integration” is a meter running. The RevOps as a service discussion on this site walks through the same buy-versus-meter logic for adjacent work.
A named lead who stays through delivery
Firms that sell with partners and deliver with juniors are a known failure mode. Insist that the person who scopes the work is accountable through delivery, and put continuity of the named lead in the contract.
Knowledge transfer built in, not bolted on
The engagement should leave the portfolio company able to run the integrated systems without the consultant. If there is no plan for handover to the internal team, you are buying a dependency, not a capability. This matters more when the platform intends further add-ons, where a repeatable playbook is worth more than a single clean integration.
Alignment on the deal calendar
Milestones should map to real triggers: Day 1, the first combined board meeting, the first full-quarter close, peak trading season, and any covenant reporting date. Harvard Law School’s corporate governance forum publishes regularly on post-merger governance and reporting obligations; the material at the Harvard Law School Forum on Corporate Governance is useful when setting those milestones against fiduciary and reporting expectations. (Anything touching legal or reporting duty is a question for counsel, not the integration lead.)
7. How to judge the work in flight
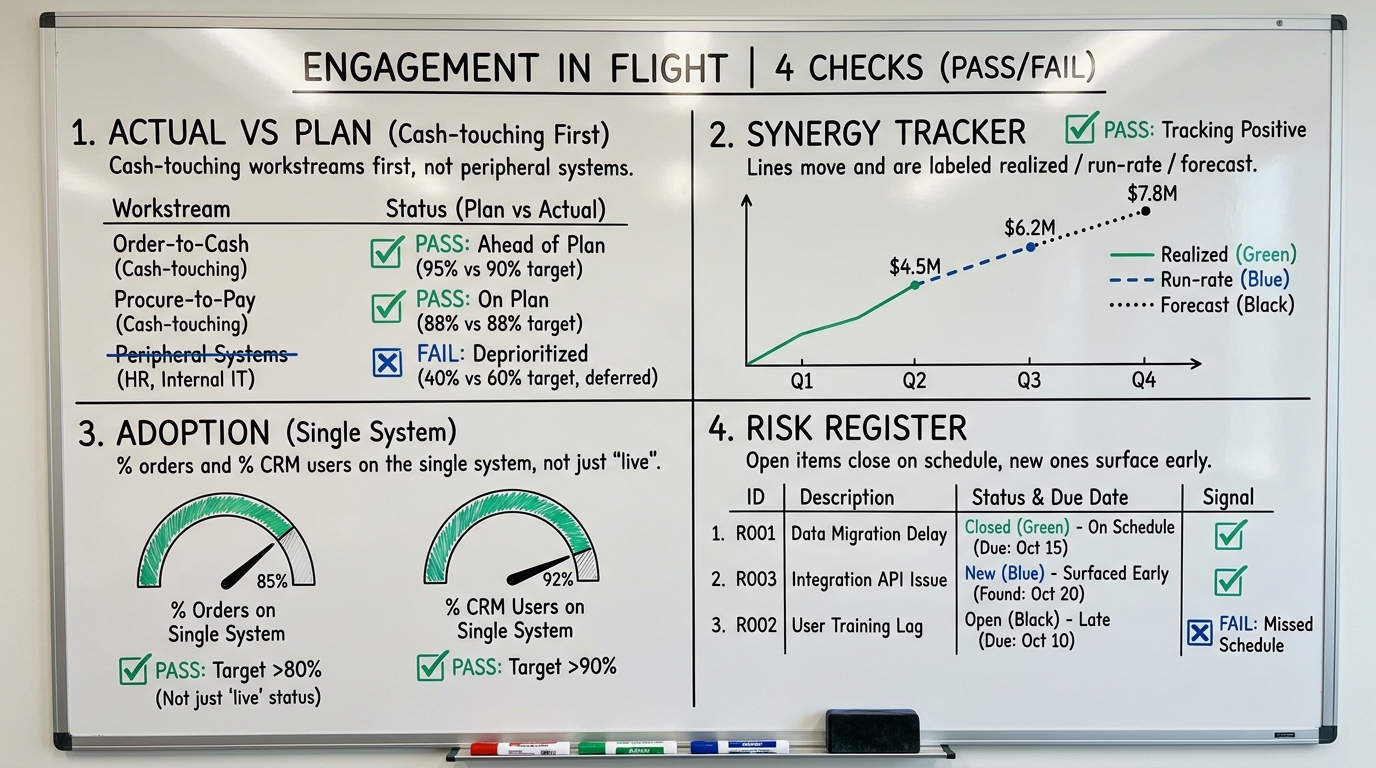
The buyer’s oversight job does not end at the signature. A handful of checks, applied at each steering meeting, tell you whether the engagement is on track long before the milestone dates arrive.
Actual versus plan on the workstreams that touch cash
Ask for the status of financial consolidation and order-to-cash first, every time. Progress on peripheral systems while these lag is a signal the consultant is working the easy parts.
Movement on the synergy tracker
Each steering meeting should show which synergy lines have moved and by how much, classified honestly as realized, run-rate, or still forecast. A tracker where everything stays “in progress” for two months is a tracker nobody believes.
Adoption, not just deployment
A system that is live but unused delivers no synergy. Ask for usage evidence: what percentage of orders now flow through the consolidated system, how many users are active on the single CRM. Research on how people actually engage with information, including the UX findings summarized in UX research on interactive infographics, is a reminder that a tool nobody adopts is a cost, not a capability.
A shrinking risk register
Open risks should close on schedule and new ones should surface early. A register that only grows, or one that never changes, both signal a problem.
PitchBook and S&P Global Market Intelligence both track deal and integration data that can help you benchmark whether your timeline is reasonable for the sector and deal size; see PitchBook and S&P Global Market Intelligence. Preqin’s alternative assets data at Preqin is another reference for how value creation timelines are trending across the asset class.
8. Common ways the hire goes wrong
Most bad outcomes trace to a few recognizable patterns, and each has a tell the buyer can catch early.
- Discovery that never ends. The consultant keeps mapping and never commits to a plan. Tell: no dependency map by week three.
- A technology answer to a decision problem. They recommend new systems before the model choice is settled. Tell: a platform recommendation before the absorb-versus-best-of-breed decision is made.
- Activity dressed as progress. Reports full of tickets closed and hours logged, thin on synergy or cash impact. Tell: a status deck with no line back to the deal model.
- The bait-and-switch team. Senior in the pitch, junior in delivery. Tell: reluctance to name the delivery lead in the contract.
- No handover. The work leaves the portfolio company more dependent, not more capable. Tell: no knowledge-transfer plan in the scope.
Two adjacent decisions are worth keeping in view because they interact with this one. If the integration exposes a data foundation that was never built, treat it as a separate program rather than a bolt-on to integration, using data strategy consulting for portfolio companies as the frame. And if the platform lacks the internal bandwidth to sustain the integrated systems, a data team as a service arrangement can bridge the gap without a permanent hire.
9. A buyer’s checklist
Before you sign the engagement, confirm the following. If more than a couple are missing, the scope is not ready.
- The three or four integration outcomes are written down with dates and acceptance criteria.
- The integration model (absorb, best-of-breed, coexist) has been decided or is scoped to be decided in the first two weeks.
- Workstreams are sequenced finance-first, then order-to-cash, then CRM, then reporting.
- The consultant commits to a documented baseline within three weeks.
- There is a dependency map and a critical path, not just a task list.
- A synergy tracker links technical milestones to lines in the deal model.
- The risk register has owners and closure dates and is reviewed at every steering meeting.
- Milestones map to real triggers: Day 1, first combined close, first board meeting, covenant dates.
- The named delivery lead is contractually committed through delivery.
- A knowledge-transfer plan leaves the portfolio company self-sufficient.
None of this is exotic. It is the same discipline good operators apply across the value-creation plan, from the first 100 days through to exit, and it sits inside the broader private equity operating agenda rather than off to the side as an IT chore. The earlier the buyer decides what “done” looks like, the less the integration costs and the sooner the synergies show up in cash. For the strategic build-versus-buy version of this same instinct, the piece on pre-sell versus build first is a useful companion, and Harvard Business Review’s M&A collection at HBR is a good ongoing source on why integration, not the deal itself, decides whether the thesis pays.
10. Where to take this next
If you are staring at two ERPs, two CRMs, and a synergy plan that is quietly slipping to the right, the next step is a scoped integration sprint with a named owner and milestones tied to your deal model. Bring the specific integration to the DevriX and GrowthShuttle private equity team through the PE operating hub, and start from the outcomes and dates you need hit, not from a systems inventory.