

The forecast slips two quarters in a row, and nobody in the portfolio company can explain the gap with numbers everyone trusts. The CFO cites one figure, the head of sales cites another, and the board deck cites a third. That is the moment the operating partner reaches for outside help, and it is exactly the wrong moment to write a blank check for a data strategy engagement. The person accountable for revenue operations in that business is about to spend money that either buys a reliable forecast, tighter working capital, and cleaner exit diligence, or buys a 90-page slide document that sits on a shared drive.
This guide is for the operating partner and the portfolio company executive who already have budget and a mandate, not for someone learning the discipline. The question is not what data strategy is. The question is what to scope, what to refuse, and how to tell in 60 days whether the money is converting into enterprise value. Data strategy consulting for portfolio companies is worth buying only when it changes a decision the sponsor cares about: the forecast, the multiple, the cash conversion cycle, or the speed of an integration.
1. Name the commercial problem before anyone touches the data
Data work goes wrong when it starts from the data. A team gets access to the warehouse, finds it messy, and spends four months cleaning it. Clean data is not a return. The sponsor did not underwrite the deal on tidy tables.
Start instead from the decision that is currently being made badly. In a portfolio company that usually reduces to one of a short list:
- The revenue forecast is unreliable, so cash and hiring decisions are guesses.
- Nobody can attribute pipeline to spend, so marketing budget is defended by anecdote.
- The board asks for a metric and it takes three days and two analysts to produce it.
- An add-on is coming and two companies keep customer, product, and revenue data in incompatible ways.
- Exit is 18 months out and the data story will not survive a buyer’s quality of earnings review.
Each of those maps to a financial consequence: forecast reliability, EBITDA defensibility, management visibility, integration speed, and multiple protection. Bain’s annual analysis of the industry, published in its Global Private Equity Report, has for years pointed to operational value creation carrying more of the return as multiple expansion and cheap leverage do less of the lifting. Data is one of the levers, but only when it is pointed at a number the sponsor already tracks.
The first job of any credible data strategy consulting engagement is to force this conversation. If the consultant does not open by asking which decision is currently expensive and wrong, they are selling activity, not outcome.
2. Decide whether this is a strategy problem or an execution problem
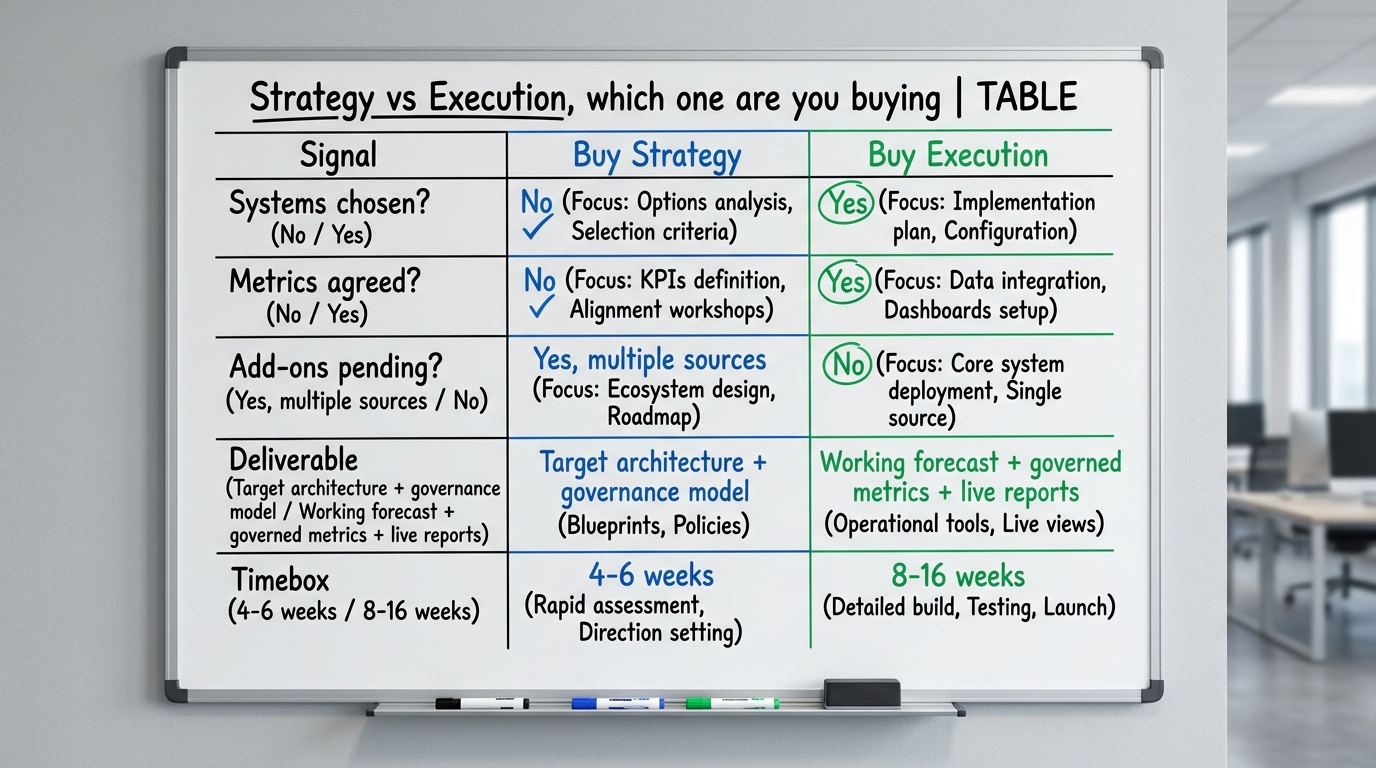
Executives conflate two different purchases. One is deciding what the data estate should become. The other is building it. Buying the first when you need the second wastes a quarter.
When you actually need strategy
Strategy work earns its fee when there is genuine ambiguity about direction: multiple source systems with no agreed system of record, a pending platform decision, an add-on program that will multiply the number of data sources, or a leadership team that cannot agree on which metrics define the business. In those cases a short, opinionated strategy phase prevents an expensive build in the wrong direction.
When strategy is a stall
If the metrics are known and the systems are already chosen, a long strategy phase is a way to bill without committing to a result. In many mid-market portfolio companies the answer is not a new data architecture. It is a working forecast model, a governed set of definitions, and one reliable pipeline report. That is closer to a focused RevOps build than a strategy deck. The distinction matters for scope and for price, and it is the same distinction that separates a real RevOps-as-a-service engagement from a retainer that never ships.
3. Scope the engagement around a decision, not a deliverable
The scoping document is where value is won or lost. A weak scope lists artifacts: a data audit, a maturity assessment, a roadmap, a governance framework. Those describe what the consultant will produce, not what the company will be able to do afterward.
A strong scope names the decision that gets better and the owner who will make it. For example, an illustrative scope for a struggling forecast reads: within ten weeks, the CFO can produce a bottom-up revenue forecast from the CRM and finance system that ties to actuals within an agreed variance, with named owners for each input and a defined refresh cadence. That sentence contains an outcome, an owner, a timebox, and a test.
Insist that every workstream in the statement of work carry three things:
- The decision it improves, in the sponsor’s language.
- A named owner inside the portfolio company who inherits it, so the work does not leave with the consultant.
- An evidence test that shows it worked, expressed as a number moving or a report that did not exist before.
McKinsey’s research on private capital and operational performance repeatedly lands on the same point across its value-creation work: transformation value comes from a small number of measurable moves owned by line leaders, not from broad capability programs owned by nobody. The scope should read the same way.
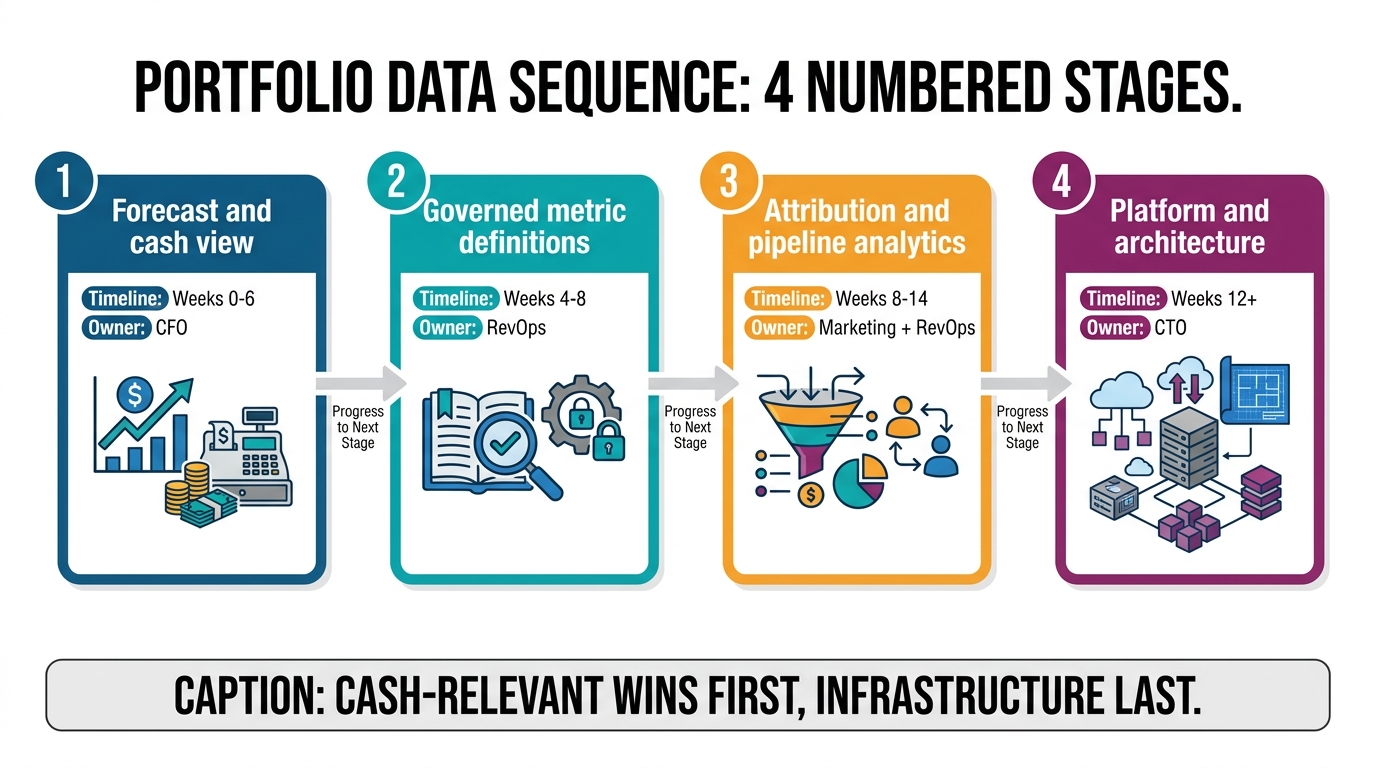
4. Sequence the work so cash-relevant wins come first
A portfolio company does not have the patience of a Fortune 500 transformation office. The hold period is finite and the board meets quarterly. Sequencing is therefore part of the strategy, not an afterthought.
First, the forecast and the cash picture
The fastest path to credibility with a sponsor is a forecast the board believes and a clear view of cash conversion. That work touches the CRM, the finance system, and the definitions that connect them. It is narrow, it is high-value, and it produces something visible at the next board meeting. The AICPA and CIMA’s work on finance and FP&A practice is a reasonable external anchor for what a defensible forecasting and management-reporting standard looks like.
Second, the metric definitions everyone will argue about
Bookings, revenue, churn, pipeline, and CAC mean different things to different teams. Governing those definitions is unglamorous and it is where most of the trust in the numbers is actually built. Do this before building dashboards, or the dashboards will encode the disagreement instead of resolving it.
Third, attribution and pipeline analytics
Only once the base is clean does attribution work pay off. Building attribution reporting on ungoverned data produces confident charts built on quicksand. Sequence it third, not first, no matter how loudly marketing wants it first.
Fourth, the platform and architecture moves
Warehouse consolidation, a CDP, or a new BI layer are real projects, but they are rarely the thing that changes the next board meeting. They belong later in the sequence unless an add-on or a system migration forces the timing.
5. Tie the engagement to the deal clock
The value of data work depends heavily on where the company is in the hold. The same engagement is worth different amounts at different moments, and the trigger should shape both scope and urgency.
During diligence
Before the deal closes, data work is about validating the number, not improving it. The question is whether the target’s reported metrics survive scrutiny and whether the systems can produce clean evidence at all. This overlaps directly with RevOps due diligence and with broader technology due diligence, where the data estate is often the single largest source of hidden risk. If pipeline and revenue cannot be reconstructed from the systems, that is a finding, not a footnote.
In the first 100 days
The window right after close is when data strategy earns the most, because the reporting baseline set now becomes the yardstick for the entire hold. Getting the forecast and the metric definitions right in the first 100 days means every subsequent board conversation runs on the same numbers. Getting it wrong means re-litigating definitions at every meeting.
Approaching an add-on
When an add-on is on the table, the data question becomes integration speed. Two companies with incompatible customer and revenue models will spend months reconciling before anyone can see a combined pipeline. Deciding the target system of record and the mapping approach before the ink dries is what keeps synergy timelines honest. BCG’s work on principal investors and post-merger integration is a useful external reference for how integration cost and pace are underestimated when data is treated as an afterthought.
Approaching exit
Twelve to eighteen months out, the lens flips again. Now the job is to make the data story survive a buyer’s quality of earnings and a technical review. Harvard Business Review’s coverage of mergers and acquisitions and the Harvard Law School Forum on Corporate Governance both document how much of a transaction’s friction comes from information quality on the sell side. A clean, well-governed data estate at exit is a multiple defense.
6. Judge the consultant on evidence, not on the deck
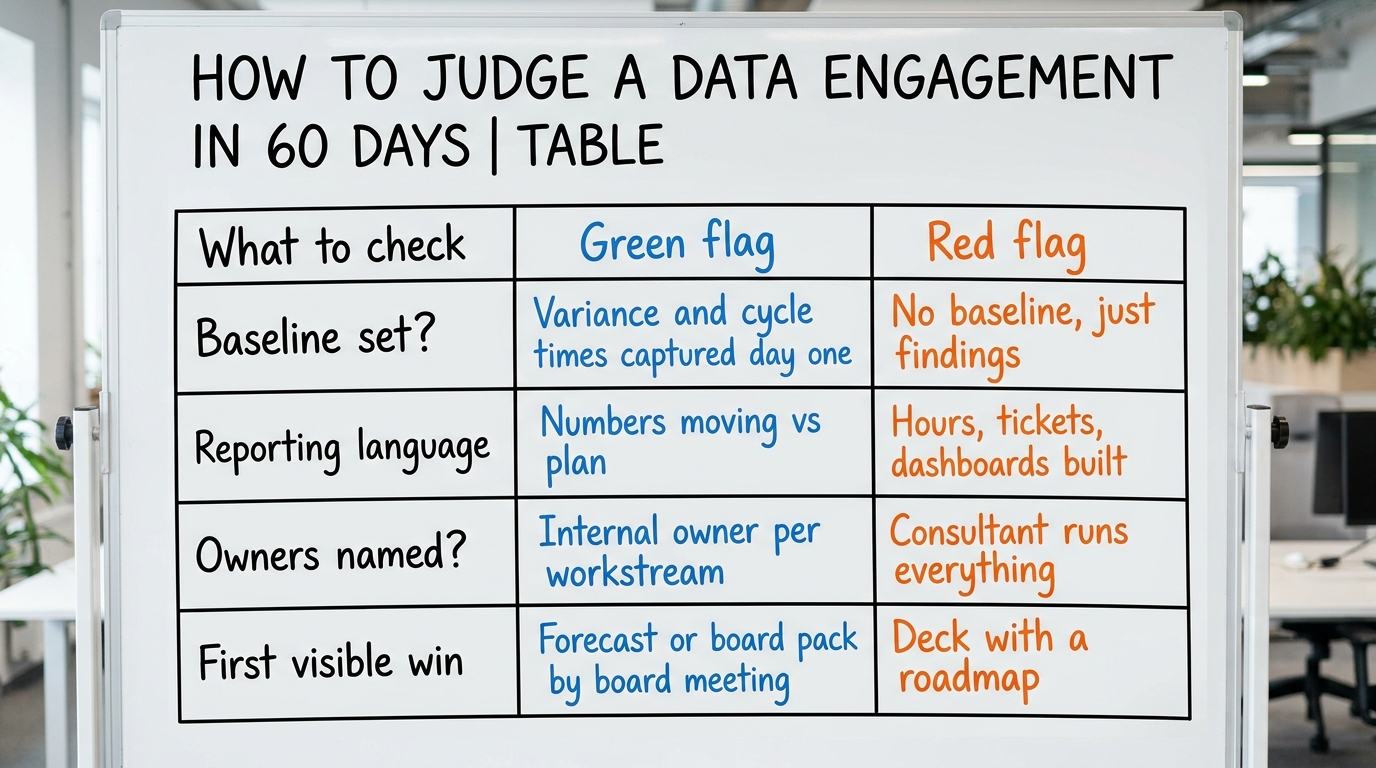
The person accountable for revenue operations should evaluate a data strategy consulting firm the same way a sponsor evaluates a management team: on baselines, owners, and results against plan.
Ask what they will measure on day one
A serious firm establishes a baseline before it changes anything: current forecast variance, time to produce the board pack, number of conflicting metric definitions, percentage of pipeline that reconciles to the finance system. If they cannot tell you what they will measure at the start, they cannot prove improvement at the end.
Watch for the vendor register
Be wary of firms that report progress in hours logged, tickets closed, dashboards built, and models trained. Those are inputs. They tell you the vendor was busy. They do not tell you the forecast got more accurate or the board pack got faster. The right status update is expressed in the numbers the baseline captured. This is the same discipline that separates a strong RevOps partner from a busy one, covered in more depth in the guide to choosing and judging a RevOps agency.
Insist on knowledge transfer, not dependency
The engagement should leave capability inside the company. If every report requires the consultant to run it, the company has rented a metric, not built one. Named internal owners for each workstream are the mechanism. If the scope has no owners, the work will walk out the door with the invoice.
7. Watch the platform decision hiding inside the strategy
A data strategy for a portfolio company almost always contains an implicit platform bet. The CRM and marketing platform decide what data even exists to strategize about. In many mid-market companies that platform is HubSpot or Salesforce, and the quality of the implementation caps the quality of every downstream analysis.
This is why a data strategy that ignores the state of the operational systems is incomplete. If the CRM is poorly configured, the cleanest analytics layer in the world reports on garbage. The decisions around a HubSpot implementation for a portfolio company and the broader question of HubSpot across a private equity portfolio are not separate from data strategy. They are upstream of it. A good consultant will tell you when the real problem is the source system rather than the reporting.
The same caution applies to data sources that look impressive but degrade trust. Vanity signals, purchased data, and manipulated inputs poison a forecast the same way incentivized reviews trigger platform penalties in a marketing context. Clean inputs are a governance decision, not a technical one.
8. Right-size the spend against the hold and the return
Budget discipline on data work is the same as budget discipline on any value-creation lever. The spend should be proportional to the enterprise-value swing it protects or creates, and it should be phased so the sponsor can stop after the first visible win if the return is not materializing.
Practical guardrails for the person holding the budget:
- Phase the contract. A short, fixed-scope first phase that produces a working forecast and governed definitions. Renew into the platform work only if phase one converts.
- Cap the strategy phase. If the strategy phase runs longer than the execution phase, the balance is wrong for a portfolio company timeline.
- Tie later phases to triggers. Warehouse consolidation waits for the add-on. The BI rebuild waits for the exit prep. Do not fund infrastructure ahead of the event that needs it.
- Classify the value honestly. A faster board pack is a realized operating improvement. A forecast that will support a covenant conversation is run-rate. A clean exit data story is enabled value, not money in the bank today. Do not let enabled value be sold as realized.
Data providers such as PitchBook, Preqin, and S&P Global Market Intelligence track how operational value creation has become the primary source of return across the industry, and the trade press including Private Equity International, Buyouts, and PE Hub covers the same shift in deal after deal. The implication for data spend is direct: it competes with every other value-creation dollar, so it has to show up in a number the sponsor already watches.
9. A decision checklist for the person holding the budget
Before signing a data strategy consulting engagement for a portfolio company, run the scope against this list. If the answer to any item is no, the scope is not ready.
- Does the scope name the specific decision that will get better, in the sponsor’s language, rather than list deliverables?
- Is there a named internal owner for each workstream who inherits the capability?
- Is there a baseline being captured before anyone changes anything?
- Does the sequence put the forecast and cash view first and the platform build last?
- Is the engagement tied to a real trigger: diligence, first 100 days, an add-on, a system migration, or exit prep?
- Is the first visible win due by the next board meeting, not at the end of a six-month roadmap?
- Are status updates expressed as numbers moving against the baseline, not hours and tickets?
- Is the contract phased so you can stop after phase one if the return does not appear?
- Has the consultant flagged whether the real constraint is the source system rather than the reporting layer?
- Is the value classified honestly as realized, run-rate, or enabled?
Data strategy consulting for portfolio companies is not a discovery exercise and it is not a capability program. It is a set of narrow moves that make a forecast believable, a board pack fast, an integration quicker, and an exit cleaner. Judged against those outcomes, most of the market’s polished decks fail and a small number of focused engagements pay for themselves inside a hold. The buyer’s job is to tell the two apart before the money moves, not after.
When the scope is right and the sequencing is honest, the person accountable for revenue operations walks into the next board meeting with numbers nobody argues about. That is the whole point.
To scope a data and analytics engagement against a specific portfolio company’s forecast, board reporting, and exit readiness, review the DevriX private equity operating hub and bring the decision you need the data to improve.