
The deal is signed. The value creation plan says integration delivers a chunk of the return, and the first board meeting is six weeks out. Now the operating partner and the portfolio company executive face a narrower question than the one the deal team asked: who runs the integration, what gets integrated first, and how will anyone know whether it is working. Post merger integration consulting in private equity is bought to answer those three questions faster and with less risk than an internal team could alone. The problem is that most of the market sells activity, and the buyer with budget needs to distinguish a firm that moves synergy into the P&L from one that produces a workplan and a status deck.
This guide is for the person accountable for revenue and operating results after close, not for someone learning the field. It lays out what actually has to be decided, how to scope the engagement, and how to judge the work while it is happening rather than in the post-mortem.
1. Why integration is where the return leaks
The synergy case underwrites the price. When integration slips, the leak shows up in three places at once: revenue dis-synergy as customers and reps churn during the disruption, cost synergies that arrive late or never, and management attention pulled off the core business into cleanup. Bain’s annual private equity report has tracked for years how much of fund-level return now depends on operational improvement rather than multiple expansion, which is precisely the work integration either delivers or fumbles. You can read the current view in the Bain & Company Global Private Equity Report.
The commercial consequence is direct. A synergy target of, say, several hundred basis points of EBITDA margin sits inside the model whether or not anyone owns delivering it. If the integration is run as a series of workstream meetings with no baseline and no owner tied to a number, the synergy quietly reclassifies from realized to forecast, then from forecast to hope. McKinsey’s ongoing work on merger management, available through McKinsey’s private capital research, has repeatedly found that integrations fail on execution discipline, not on strategy. The consulting decision is therefore an execution decision, not a strategy decision.
2. Decide what “integration” actually covers before you scope a firm
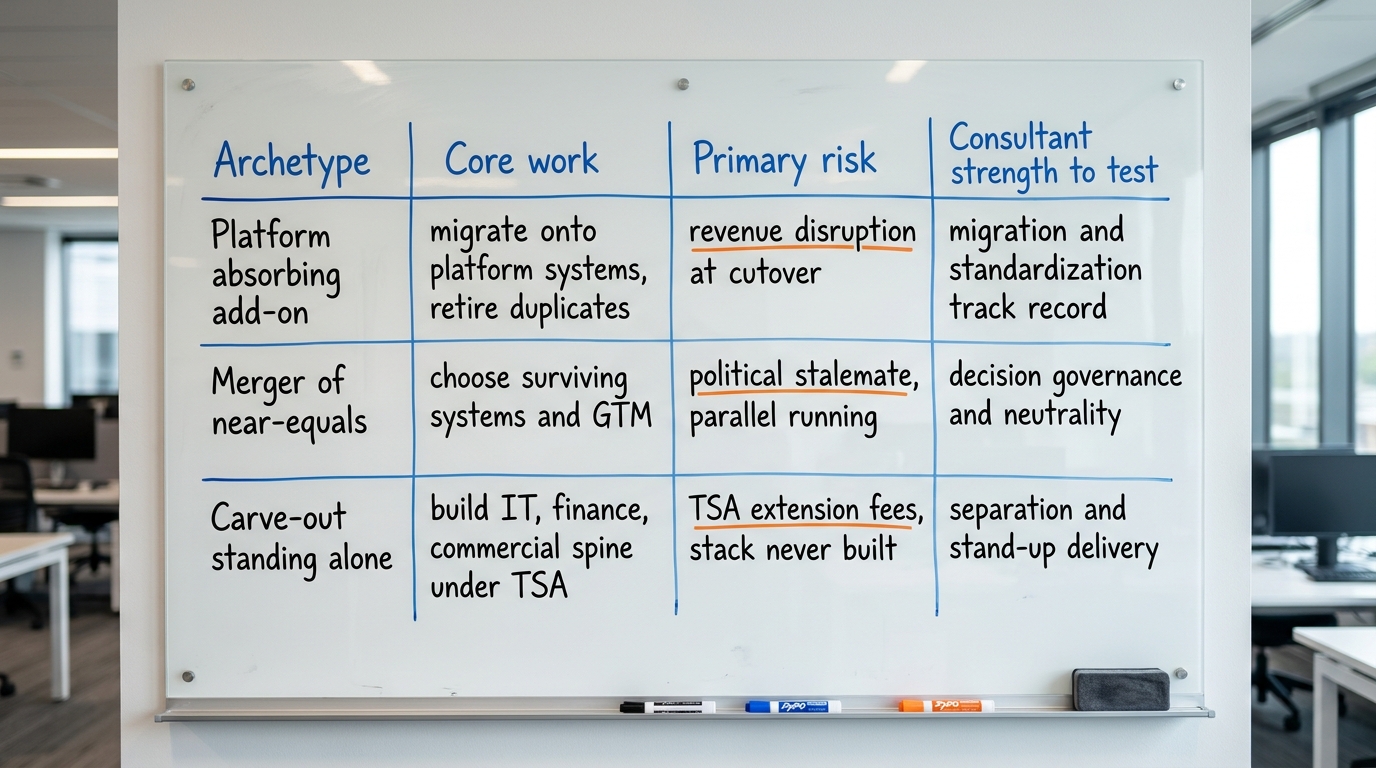
“Post merger integration” is a container word. Before scoping any firm, the operating partner should force the deal thesis into a specific list of what is being combined and what is being left alone. Three archetypes cover most PE situations, and each demands a different consultant.
Platform absorbing an add-on
The platform already has systems, a finance function and a brand. The add-on gets pulled onto them. Here the work is migration and standardization: move the acquired company onto the platform’s ERP, CRM and reporting cadence, retire duplicate tooling, and rebrand where the commercial case supports it. The risk is customer and revenue disruption during cutover. This is the terrain covered in more depth in buy and build technology integration.
Merger of near-equals
Two comparable businesses combine and neither system set is obviously superior. Now the work includes contested decisions about which platform survives, whose sales process wins, and how the combined go-to-market is organized. The risk is political drift and a stalemate that leaves both companies running in parallel for a year.
Carve-out standing up on its own
The acquired unit is separating from a parent and must build its own IT, finance and commercial spine, often under a Transition Services Agreement clock. The failure mode is TSA extension fees and an operating stack that was never really built. The judging criteria for this specific case are covered in how to hire and judge a carve-out IT separation consultant.
A firm that is excellent at add-on absorption may be weak at carve-out separation. Naming the archetype first prevents hiring the wrong specialist for the right budget.
3. Separate the strategic call from the execution engine
Two distinct jobs get bundled under “PMI consulting,” and paying one rate for both is a common overspend. The first is the integration blueprint: sequencing, synergy targeting, the governance structure, the Day 1 readiness list. This is a few weeks of senior work. The second is execution management: running the integration management office, chasing owners, tracking actual versus plan, and forcing decisions when workstreams stall. This runs for the length of the integration.
The operating partner should decide which of these to buy externally. In many portfolio companies the executive team can run execution if someone hands them a credible blueprint and a tracking discipline. In others the team is stretched thin by the deal itself and needs an external integration lead for the first two or three quarters. The Harvard Law School Forum on Corporate Governance publishes practitioner analysis on integration governance that is useful for pressure-testing how decision rights should be structured across the two jobs.
A firm that only sells the blueprint will leave you with a beautiful plan and no delivery. A firm that only sells bodies to run meetings will leave you with motion and no thesis. The scope should name both and price them separately so the buyer can turn one off.
4. Anchor everything to a baseline, or the work is unauditable
The single most common failure in integration consulting is starting delivery before the baseline is fixed. If nobody wrote down current-state revenue by segment, current cost structure, current system inventory and current headcount before Day 1, then no one can prove synergy was realized later. The number just becomes an assertion.
Insist that the first deliverable is a baseline the CFO signs. That includes a synergy register with each line classified honestly: realized in the P&L, run-rate but not yet annualized, forecast, or merely enabled by a capability now in place. Guidance from AICPA and CIMA on business combinations and measurement is a reasonable reference point for how rigorously combined financials should be constructed. The point is not accounting for its own sake. It is that the board meeting in week six will ask “are we on plan,” and only a baseline lets anyone answer.
This discipline is the same one that should have run in diligence. If it did not, the integration team inherits the gap. The relationship between the two phases is spelled out in digital due diligence for acquisition: what to decide before you sign and in RevOps due diligence in private equity.
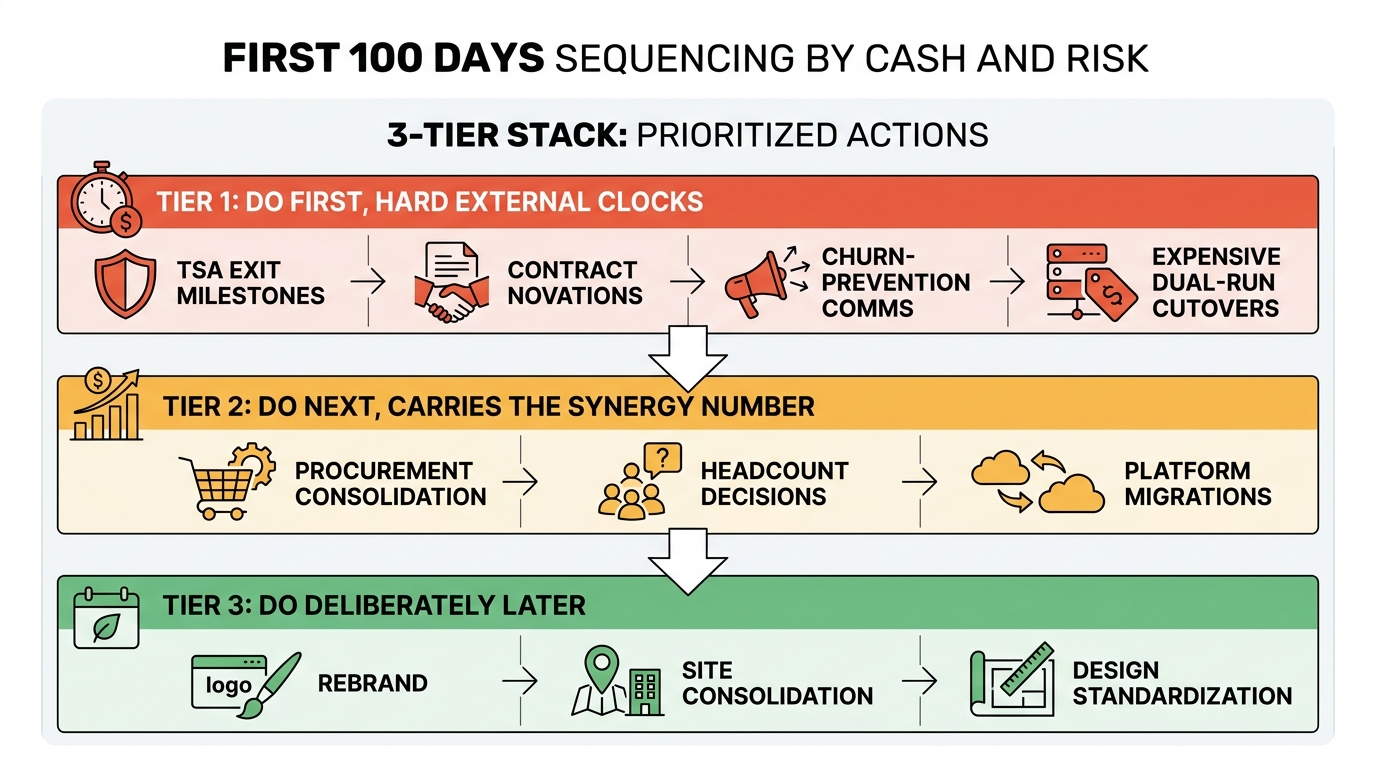
5. Sequence the first 100 days by cash and risk, not by comfort
The instinct after close is to start with the easy, visible work: a rebrand, a new website, a town hall. That order burns the window. The first 100 days should be sequenced by two variables: how much cash or risk a workstream carries, and how much it degrades if you wait.
Do first: the things that fail if delayed
TSA exit milestones, contract novations with hard dates, customer communications that prevent churn, and any system cutover that gets more expensive the longer both stacks run. These have external clocks and cannot be recovered later.
Do next: the synergy actions that need setup
Procurement consolidation, headcount decisions, and platform migrations that require sequencing and testing. These carry the bulk of the synergy number and deserve the most disciplined tracking.
Do deliberately later: brand and surface changes
Rebranding, site consolidation and design standardization matter, but they rarely fail if they wait a quarter, and rushing them during cutover raises risk. When you do reach them, the practical craft questions, down to how the combined properties handle choosing font sizes for responsive pages, deserve real attention rather than a rushed template swap. The structured view of this window is laid out in the first 100 days playbook.
Harvard Business Review’s collected work on mergers and acquisitions is consistent on this: value erodes fastest in the early weeks when customer-facing continuity breaks, which is why revenue protection outranks internal tidiness in the sequence.
6. Judge the technology and RevOps integration on its own merits
Systems and commercial operations are where integration promises most often quietly die. Two CRMs that never merge mean the pipeline number is a guess. Two ERPs mean the CFO cannot close the combined books cleanly. A consultant who treats technology as an afterthought to the org chart will leave the business unable to report on itself.
The operating partner should require a technical integration view early, ideally informed by the technology due diligence already done. That view should state, per system, whether the plan is migrate, retire, keep both, or rebuild, with an owner and a date for each. On the commercial side, the combined revenue engine needs a maturity read so the team knows what it is actually integrating. The practical instrument for that is described in the RevOps maturity assessment an operating partner can actually use, and the ongoing operating model options are covered in RevOps as a service in private equity.
A useful test: ask a candidate firm how they would combine two pipelines with different stage definitions and different data hygiene. A firm that answers with a data model, a mapping approach and a cutover plan is credible. A firm that answers with “we will run a workshop” is selling meetings.
7. How to scope the engagement so you can turn it off
The commercial fit for most mid-market integrations is a focused engagement in the range of roughly $25K to $75K for a blueprint plus early execution support, not an open-ended retainer that bills for status decks. Scope it so the buyer holds the off switch.
Fixed first phase with a named output
The first phase should be a fixed-fee sprint producing the baseline, the synergy register, the sequenced integration plan and the Day 1 readiness list. It ends on a date with a deliverable the CFO and operating partner can accept or reject.
Execution support with explicit exit criteria
If external execution support follows, define what “done” means: TSA fully exited, both systems consolidated, synergy register at a stated percentage realized. Without exit criteria, execution support becomes a permanent line item. This is the same buy-versus-build discipline discussed in pre-sell vs build first for SMEs, applied to the integration function itself.
Reporting the board can read in five minutes
The output the board needs is not a 40-slide deck. It is a one-page synergy register showing target, realized, run-rate and forecast, plus a short risk list with owners. Research on how decision-makers actually absorb dense visuals, summarized in UX research on interactive infographics, supports keeping board reporting tight and scannable rather than exhaustive.
8. What good looks like at each board meeting
Judge the engagement by what shows up at the board, not by hours logged. At the first meeting after close, expect a signed baseline and a sequenced plan with owners. By the second, expect movement on the hard-clock items and honest classification of what is realized versus forecast. By the third, expect the synergy register to show realized value climbing toward the model and the risk register shrinking.
Warning signs are specific: the plan keeps getting reissued but the synergy register never moves; every workstream is “green” while the combined financials are not yet consolidated; the consultant reports activity volume instead of value moved into the P&L. Data providers such as PitchBook and S&P Global Market Intelligence track how integration and holding-period execution correlate with outcomes at exit, which is a reminder that the board is watching this because it shows up in the eventual sale process. Practitioner outlets including Private Equity International and Buyouts regularly document deals where integration under-delivery became the story at exit.
9. How to run the selection itself
Shortlist on the archetype match from section 2, not on brand name. Ask each firm for a named integration lead and confirm that person, not a partner who disappears after the pitch, will run the work. Require a written statement of what they will deliver in the first fixed phase and what they will not do. Check references on integrations of the same archetype and roughly the same size.
Firms that publish credible integration thinking, and research houses like BCG that maintain principal-investor and PE practices, are useful for calibrating what mature methodology looks like. But the decision is made on the specificity of the scope and the credibility of the named lead, not on the thought-leadership library. If the proposal cannot tell you what the first deliverable is and when the CFO gets to accept it, the firm is selling motion.
10. The decision-and-judgment checklist
Before signing an integration consulting engagement, the operating partner and portfolio executive should be able to answer yes to each of these:
- The integration archetype is named (add-on absorption, merger of near-equals, or carve-out), and the shortlisted firm has done that specific type.
- The blueprint and the execution engine are scoped and priced separately, so either can be turned off.
- The first deliverable is a CFO-signed baseline plus a synergy register classified as realized, run-rate, forecast or enabled.
- The first 100 days are sequenced by cash and risk, with hard-clock items first and brand work deliberately later.
- Every system has a named decision (migrate, retire, keep, rebuild) with an owner and a date.
- The combined revenue engine has a maturity read before anyone starts merging pipelines.
- Execution support, if bought, has explicit exit criteria tied to synergy realized and TSA exit.
- Board reporting is a one-page register plus a risk list, not a status deck.
- A named integration lead, confirmed in writing, runs the work through delivery.
An engagement that clears this list is buying enterprise-value improvement. One that cannot is buying you a workplan and a monthly meeting, which the portfolio company can produce for free.
11. Where to take this next
If integration sits inside the value creation plan for a deal at or after close, the useful next step is a scoped assessment that produces the baseline, the synergy register and the sequenced plan the board will actually judge, rather than another retained advisor. Review the integration and PMI offer in the DevriX private equity hub and match it against the archetype and the board timeline this guide describes.