

A buy-and-build thesis rarely fails on the model. It fails on the plumbing. The synergy case assumes two, three, or five acquired businesses will book revenue on one system, report EBITDA on one chart of accounts, and let one management team see the numbers by the same close date every month. The technology that has to make that true is almost always underfunded, discovered late, and handed to a portfolio company executive who was hired to run a business, not to run three CRM migrations at once.
If a platform is about to sign its second or third add-on, the person accountable for revenue operations needs to make a small number of consequential decisions about buy and build technology integration before the invoices start landing. Get those decisions right and the integration cost stays inside the deal model. Get them wrong and the synergy timeline slips two quarters, the CFO loses forecast reliability across the group, and the next add-on inherits a mess that compounds. This guide is for the operator with budget and a live problem, not for someone learning the category.
1. Why buy-and-build breaks on the systems layer
The commercial logic of buy-and-build is well documented. Bain’s annual Global Private Equity Report has tracked the strategy’s rise as sponsors lean on multiple arbitrage and operational scale rather than leverage alone. Firms like BCG and McKinsey have published extensively on why the add-on machine is attractive: buy small at a low multiple, fold into the platform, sell the whole at a higher one.
What that literature is honest about, and what deal models often are not, is that the value only shows up when the acquired business actually operates as part of the platform. That means shared systems, shared data, and a shared way of reporting. Until then, an add-on is a separate company that happens to have the same owner. The revenue synergy line, the cross-sell, the consolidated pipeline view, all of it depends on integration work that lives outside the finance team’s spreadsheet and inside a stack no one fully mapped during confirmatory diligence.
The failure pattern is predictable. Two businesses run different CRMs, different billing, different definitions of a qualified lead and a closed deal. The platform’s board wants a single revenue picture by the second month. The RevOps owner discovers the acquired company logs opportunities in a way that cannot be reconciled with the platform’s without rebuilding the data model. The synergy timeline was set by people who never saw the systems. That gap is the subject of this guide.
Before any of the sequencing below matters, the RevOps owner should have a defensible read on where the acquired stack actually stands. A RevOps maturity assessment that survives a board meeting is the fastest way to turn a vague “their systems are a mess” into an evidence-backed baseline the board will accept.
2. The one decision that governs everything: adopt, migrate, or coexist
Before any tooling conversation, the operator has to make a single architectural choice for each acquired business. Everything downstream, cost, timeline, disruption, and how you measure success, follows from it.
Adopt the platform’s stack
The add-on moves onto the platform’s CRM, billing, and reporting. This is the cleanest end state and the one that most directly delivers the consolidated management visibility the board wants. It is also the most disruptive to the acquired team, who lose their tools and their muscle memory in the first months of new ownership.
Migrate to a new shared target
Neither business’s stack is good enough, so the group standardizes on a new platform both will move to. This is the right call when the platform’s own systems are already a constraint on growth, but it doubles the change management load because the platform team is migrating too.
Coexist with a reporting bridge
The acquired systems stay in place, and integration happens at the data layer: a shared warehouse and a common reporting model pull both into one view without forcing a full migration. This preserves operational continuity and buys time, at the cost of running two stacks and the ongoing reconciliation that implies.
There is no universally correct answer, and the wrong instinct is to default to “adopt” because it feels tidy. The decision should be made against the hold thesis: if three more add-ons are coming in eighteen months, a repeatable reporting bridge often beats a heroic one-time migration that no one can run again. This is the same tradeoff that governs a data platform implementation in a portfolio company, and the two decisions should be made together, not in sequence.

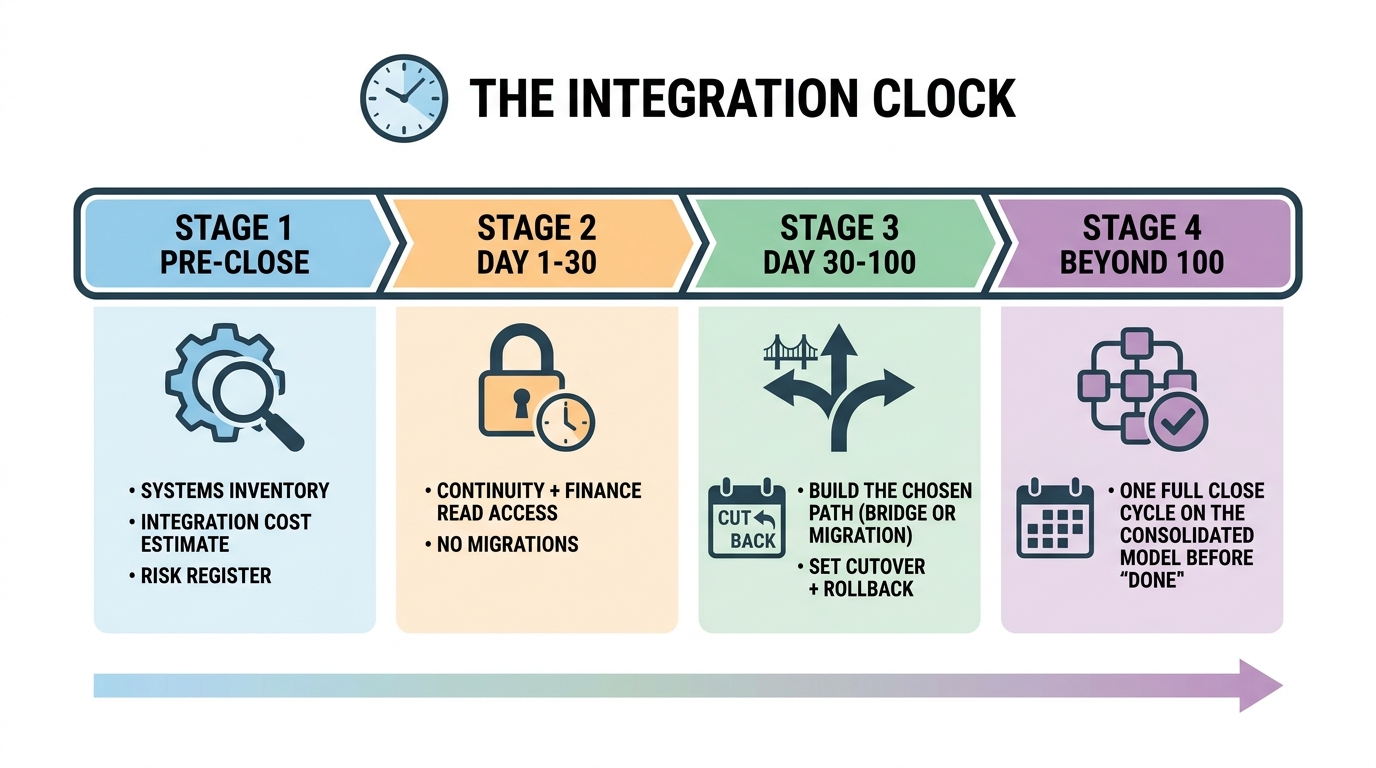
3. Sequence the integration against the deal clock, not the org chart
Once the path is chosen, the work has to be sequenced against the events that actually create pressure: close, Day 1, the first board meeting, the first consolidated month-end. The mistake is sequencing by technical dependency alone and letting the board’s expectation of visibility collide with a migration that was never going to finish in time.
Confirmatory diligence and pre-close
The systems inventory belongs here, not after close. A proper technology due diligence pass on the target should produce the integration cost estimate and the risk register the model needs. If the RevOps stack was never examined before the number was funded, the operator is now pricing surprises. The companion discipline of RevOps due diligence before you fund the number is what keeps integration from becoming a post-close discovery exercise.
Day 1 to Day 30
The only technology goals in the first month are continuity and control. Payroll runs, invoices go out, revenue keeps flowing, and the platform gets read access to the acquired systems so finance can see the numbers, even if the model is ugly. Nobody should be migrating a CRM in week two. The first 100 days plan should protect operations first and stage the real integration for when the acquired team is stable.
Day 30 to Day 100
This is the window for the chosen path. If it is a reporting bridge, the warehouse and the shared model get built here. If it is adoption, the migration is scoped, data is mapped, and the cutover date is set with a rollback plan. The first board meeting inside this window should show a credible integration plan with owners and dates, not a finished state.
Beyond Day 100
The consolidated reporting has to hold through at least one full close cycle before anyone declares the integration done. Harvard Law School’s Forum on Corporate Governance has published useful material on post-merger integration governance that reinforces the point: integration is a governed program with milestones, not an IT ticket that closes.
4. Decide what “one number” actually means
The board wants a single revenue view. That sentence hides three separate decisions the RevOps owner has to make explicit, because each has a different cost and a different failure mode.
Common definitions before common tools
Two businesses will define a lead, an opportunity stage, a booking, and recognized revenue differently. Standardizing tools without first standardizing definitions produces a clean-looking dashboard built on incompatible data. The definitions work is unglamorous and it is where the real integration lives. It should be done on paper before anyone touches a system.
The pipeline model and attribution
If the group intends to report cross-sell and marketing-sourced revenue across the combined entity, the attribution model has to be consistent. Getting HubSpot attribution reports right for ROI measurement across two merged businesses is materially harder than doing it for one, because the underlying campaign and source taxonomies rarely match.
Close cadence and reconciliation
The CFO needs the combined entity to close on the same calendar. If one business closes on day five and the other on day fifteen, the consolidated number is always stale by design. Aligning the close is as much a systems decision as a finance one, and the AICPA’s guidance via AICPA and CIMA on financial reporting quality is a reasonable external reference for why this matters to forecast reliability.
5. Scope the work so you can price and judge it
Integration work goes over budget when it is scoped as “connect the systems” instead of as a bounded set of deliverables with acceptance criteria. The RevOps owner should insist on a scope that names the end state, the data in play, and the definition of done for each workstream.
- Data model and definitions, the agreed dictionary of lead, opportunity, booking, and revenue, signed off by both businesses’ commercial leads.
- System of record, which platform is authoritative for each object, and where the others read from it.
- Migration or bridge build, the actual engineering, with a mapped field-level plan for anything that moves.
- Reporting layer, the consolidated dashboards the board will actually look at, tied to the definitions above.
- Cutover and rollback, the plan for switching over and the plan for un-switching if it breaks.
Each of those should have an owner, a date, and an acceptance test. If the vendor or internal team cannot tell you how they will prove a workstream is done, the workstream is not scoped. This is the same scoping rigor the operator should apply when evaluating RevOps as a service in private equity or a data team as a service engagement, and it is the difference between a fixed-scope sprint and an open-ended retainer that bills through the roof.
6. Build or buy the integration capacity
Most portfolio companies do not have a spare senior RevOps engineer sitting idle when the second add-on closes. So the operator faces a resourcing decision under time pressure.
Internal team
Cheapest on paper, but the internal team is usually already running the platform’s own operations. Pulling them onto integration means something else slips. This only works when integration is a recurring event and the group has deliberately staffed for it.
Specialist partner on a fixed scope
An outside team that has done buy-and-build integrations before brings a repeatable playbook and does not have to learn on the deal. The risk is a partner who bills hours instead of delivering an end state. The right way to choose a RevOps agency for portfolio companies and judge it once you do applies directly here: buy a defined outcome, not a body count.
Platform-standard tooling as the forcing function
Some groups reduce the resourcing problem by standardizing the whole portfolio on one stack, so every add-on runs the same playbook. A standardized HubSpot decision across a private equity portfolio can turn integration from a bespoke project into a repeatable template, and a clean HubSpot implementation for a portfolio company at the platform level makes the next add-on materially cheaper to fold in.
7. Watch the integration risks that actually cost money
A few risks recur across buy-and-build technology integration, and each has a real dollar consequence the operator should carry on the risk register.
Data quality that surfaces after cutover
Duplicate accounts, orphaned contacts, and mismatched currencies do not show up in a demo. They show up when the sales team can’t find a customer and the board’s revenue number moves for reasons nobody can explain. Data cleansing belongs in the scope, before the migration, not after.
Revenue disruption during the switch
If reps lose their pipeline view for a week during cutover, deals slip and the quarter takes a hit that no synergy case accounted for. This is why the cutover plan needs a rollback, and why the timing should avoid quarter-end.
Compliance and reporting integrity
Where the combined entity’s reporting feeds anything a lender or a regulator sees, the integration cannot quietly change how revenue is recognized. The SEC and standard financial reporting practice both treat revenue recognition consistency as material, and an integration that alters it without documentation is a problem waiting for an audit.
The compounding add-on
The worst risk is silent: a poorly integrated second add-on becomes the broken foundation the third and fourth inherit. PitchBook and S&P Global Market Intelligence both track how add-on-heavy strategies dominate deal volume, which means the integration playbook a platform builds now gets used repeatedly. A weak one scales the weakness.
8. Judge the integration against value, not activity
A PE-backed buyer is not paying for connected systems. It is paying for the enterprise-value improvement that connected systems make possible: a reliable consolidated forecast, faster time to a single revenue view, cross-sell that can actually be measured, and a shorter, cleaner path to exit diligence. The RevOps owner should judge the integration on those outcomes, not on tickets closed or systems touched.
Useful ways to classify what an integration actually delivered:
- Realized, the combined entity now closes on one calendar with one revenue definition, proven across a full close cycle.
- Run-rate, the reporting bridge is live and producing the board’s numbers each month.
- Enabled, cross-sell is now measurable because the data model finally supports it, even if the revenue hasn’t landed yet.
- Risk avoided, a documented, consistent revenue-recognition approach that will survive exit diligence instead of surfacing as a finding.
Do not let enabled or forecast value be reported as realized. A dashboard that could show cross-sell is not cross-sell revenue. The board will make that distinction eventually, usually at the least convenient moment, so the RevOps owner should make it first. Harvard Business Review’s work on M&A is consistent on the theme that integration value is realized through disciplined execution against defined outcomes, not through the completion of the technical task list.
9. The integration decision checklist
Before signing off on the buy and build technology integration plan for an add-on, the RevOps owner should be able to answer every one of these:
- Has the acquired stack been inventoried, with an integration cost estimate the deal model actually reflects?
- Is the path chosen and justified against the hold thesis: adopt, migrate, or coexist with a bridge?
- Are the definitions of lead, opportunity, booking, and revenue agreed on paper by both businesses before any tool is touched?
- Is the system of record named for each object?
- Is the work sequenced against the deal clock, with continuity protected in the first thirty days?
- Does every workstream have an owner, a date, and an acceptance test?
- Is there a cutover plan with a rollback, timed away from quarter-end?
- Is data cleansing scoped before migration, not after?
- Can the integration’s success be stated in value terms the board recognizes, classified as realized, run-rate, enabled, or risk avoided?
- Is the playbook repeatable for the next add-on, or is this a one-time heroic effort?
If more than a couple of those answers are “not yet,” the integration is not ready to be scheduled against a board commitment. That is a better problem to find now than at the first consolidated close.
The operators who run buy-and-build well treat integration as a governed program with the same rigor private equity teams apply to the rest of the value-creation plan: named owners, dated milestones, evidence over activity, and a clear line from the systems work to the number the board cares about. Preqin’s and Private Equity International’s coverage of the strategy both point the same way, that repeatable operational execution, not deal-doing alone, is what separates the platforms that compound value from the ones that stall.
Move on the integration before the next add-on closes
If a platform is approaching its next add-on and the integration plan is still a slide instead of a scoped program with owners and acceptance tests, that is the gap to close now. A fixed-scope initiative sprint can turn the decisions in this guide into a costed, sequenced plan the board will fund. Bring the specific deal to the DevriX / GrowthShuttle private equity practice and scope the integration as a defined sprint, before the invoices and the synergy clock start running against you.